LIVE UPDATES
- 📢 Welcome to FundayForum – Explore Trending Topics
- 🌟 Discover What’s Trending Today
- Scientists discover new spotted cat species in Bolivia with only one known alive
- Katie Price makes major life decision after Lee Andrews separation
- Miley Cyrus reveals what Dolly Parton told her before death
- Zayn Malik gives furry pal a ‘Walking Dead' makeover
- Pakistan will go 'to any extent' to defend Saudi Arabia, vows ISPR DG
- SBP issues clarification on Rs10 banknote discontinuation
- Can we turn money into resilience?
- Phoebe Dynevor, Cameron Fuller say 'I do' in France: Pictures inside
- Kim Kardashian reveals health scare tied to father's death
- US approves potential $24.3bn F-35 sale to Saudi Arabia
Waqas Dar
-
Posts
11,292 -
Joined
-
Last visited
-
Days Won
555



Waqas Dar's Achievements


-
 Hazrat Yusuf (AS) – A complete Qur’anic and Tafsir biography covering his life, trials, patience, faith, forgiveness, and lessons from Surah Yusuf. Prophet Adam (AS) ➝ Prophet Idris (AS) ➝ Prophet Nuh (AS) ➝ Prophet Hud (AS) ➝ Prophet Salih (AS) ➝ Prophet Ibrahim (AS) ➝ Prophet Lut (AS) ➝ Prophet Ismail (AS) ➝ Prophet Ishaq (AS) ➝ Prophet Yaqub (AS) ➝ ★ Prophet Yusuf (AS) ➝ Prophet Ayyub (AS) ➝ Prophet Shuayb (AS) ➝ Prophet Musa (AS) ➝ Prophet Harun (AS) ➝ Prophet Dhul-Kifl (AS) ➝ Prophet Dawud (AS) ➝ Prophet Sulayman (AS) ➝ Prophet Ilyas (AS) ➝ Prophet Al-Yasa (AS) ➝ Prophet Yunus (AS) ➝ Prophet Zakariya (AS) ➝ Prophet Yahya (AS) ➝ Prophet Isa (AS) ➝ Prophet Muhammad ﷺ Prophet Yusuf (AS) – Complete Qur’anic & Tafsir Biography / حضرت یوسف علیہ السلام – مکمل قرآنی و تفسیری زندگی 🧭 1. Introduction / تعارف English: Prophet Yusuf (AS) was one of the noble prophets of Allah and the beloved son of Prophet Yaqub (AS). His life is one of the most detailed prophetic stories mentioned in the Qur’an, especially in Surah Yusuf. His story contains lessons of faith, patience, forgiveness, chastity, wisdom, leadership, and complete trust in Allah. اردو: حضرت یوسف علیہ السلام اللہ تعالیٰ کے جلیل القدر نبی اور حضرت یعقوب علیہ السلام کے محبوب بیٹے تھے۔ آپ کی زندگی کا واقعہ قرآن مجید میں خاص طور پر سورۃ یوسف میں تفصیل کے ساتھ بیان ہوا ہے۔ آپ کی زندگی ایمان، صبر، پاکدامنی، حکمت، معافی، قیادت اور اللہ پر کامل بھروسے کے عظیم اسباق پر مشتمل ہے۔ Arabic: نَحْنُ نَقُصُّ عَلَيْكَ أَحْسَنَ الْقَصَصِ Reference: Qur’an 12:3 👨👦 2. Blessed Family & Lineage / مبارک خاندان اور نسب English: Prophet Yusuf (AS) belonged to a blessed prophetic family. He was the son of Prophet Yaqub (AS), the grandson of Prophet Ishaq (AS), and the great-grandson of Prophet Ibrahim (AS). His family was honored with prophethood and divine guidance. اردو: حضرت یوسف علیہ السلام ایک مبارک نبوی خاندان سے تعلق رکھتے تھے۔ آپ حضرت یعقوب علیہ السلام کے بیٹے، حضرت اسحاق علیہ السلام کے پوتے اور حضرت ابراہیم علیہ السلام کے پڑپوتے تھے۔ آپ کا خاندان نبوت اور اللہ کی ہدایت سے عزت یافتہ خاندان تھا۔ Arabic: وَكَذَٰلِكَ يَجْتَبِيكَ رَبُّكَ وَيُعَلِّمُكَ مِن تَأْوِيلِ الْأَحَادِيثِ Reference: Qur’an 12:6 🌙 3. The Beautiful Dream / خوبصورت خواب English: Prophet Yusuf (AS) saw a remarkable dream in which he saw eleven stars, the sun, and the moon prostrating before him. Prophet Yaqub (AS) understood that the dream carried a special meaning and advised Yusuf (AS) not to tell his brothers about it. اردو: حضرت یوسف علیہ السلام نے ایک عظیم خواب دیکھا جس میں انہوں نے گیارہ ستاروں، سورج اور چاند کو اپنے سامنے سجدہ کرتے دیکھا۔ حضرت یعقوب علیہ السلام نے سمجھ لیا کہ اس خواب میں ایک خاص اشارہ ہے اور انہوں نے حضرت یوسف علیہ السلام کو ہدایت کی کہ یہ خواب اپنے بھائیوں کو نہ بتائیں۔ Arabic: إِنِّي رَأَيْتُ أَحَدَ عَشَرَ كَوْكَبًا وَالشَّمْسَ وَالْقَمَرَ رَأَيْتُهُمْ لِي سَاجِدِينَ Reference: Qur’an 12:4 💔 4. The Well – Betrayal by His Brothers / کنواں اور بھائیوں کی جدائی English: Prophet Yusuf’s (AS) brothers became jealous of the love their father showed toward him. They planned to take Yusuf (AS) away and eventually threw him into a well. They later returned to their father with a false story and Yusuf’s shirt covered with false blood. اردو: حضرت یوسف علیہ السلام کے بھائی اپنے والد کی محبت کی وجہ سے حسد میں مبتلا ہوگئے۔ انہوں نے حضرت یوسف علیہ السلام کو اپنے ساتھ لے جا کر کنویں میں ڈال دیا۔ پھر وہ جھوٹی کہانی بنا کر حضرت یعقوب علیہ السلام کے پاس واپس آئے اور حضرت یوسف علیہ السلام کی قمیص کو جھوٹے خون سے آلودہ کر دیا۔ Arabic: قَالُوا يَا أَبَانَا إِنَّا ذَهَبْنَا نَسْتَبِقُ وَتَرَكْنَا يُوسُفَ عِندَ مَتَاعِنَا فَأَكَلَهُ الذِّئْبُ Reference: Qur’an 12:17 ⛓️ 5. Egypt – From Slavery to Trial / مصر اور آزمائش English: Yusuf (AS) was found by travelers and taken to Egypt. He was sold and came into the household of a prominent Egyptian official. Despite his difficult circumstances, Allah protected him and prepared him for a greater purpose. اردو: حضرت یوسف علیہ السلام کو ایک قافلے نے کنویں سے نکالا اور مصر لے گیا۔ وہاں انہیں فروخت کر دیا گیا اور وہ ایک بااثر مصری شخص کے گھر میں پہنچے۔ مشکل حالات کے باوجود اللہ تعالیٰ نے حضرت یوسف علیہ السلام کی حفاظت فرمائی اور انہیں ایک بڑے مقصد کے لیے تیار کیا۔ Arabic: وَشَرَوْهُ بِثَمَنٍ بَخْسٍ دَرَاهِمَ مَعْدُودَةٍ Reference: Qur’an 12:20 🛡️ 6. Chastity & Temptation / پاکدامنی اور آزمائش English: One of the greatest tests in Prophet Yusuf’s (AS) life came when he was tempted by the wife of the Egyptian official. Yusuf (AS) refused the temptation and chose obedience to Allah over worldly desire. His response demonstrated extraordinary chastity and fear of Allah. اردو: حضرت یوسف علیہ السلام کی زندگی کی ایک بڑی آزمائش اس وقت آئی جب مصر کے بااثر شخص کی بیوی نے انہیں گناہ کی طرف بلایا۔ حضرت یوسف علیہ السلام نے گناہ سے انکار کیا اور دنیاوی خواہش کے مقابلے میں اللہ کی اطاعت کو ترجیح دی۔ یہ واقعہ آپ کی پاکدامنی اور اللہ کے خوف کی عظیم مثال ہے۔ Arabic: مَعَاذَ اللَّهِ إِنَّهُ رَبِّي أَحْسَنَ مَثْوَايَ Reference: Qur’an 12:23 ⛓️ 7. Prison – Patience During Hardship / قید خانہ اور صبر English: Although Prophet Yusuf (AS) was innocent, he was imprisoned. Even in prison, he remained patient and continued calling people toward the worship of Allah. He also interpreted the dreams of two prisoners by the knowledge Allah had given him. اردو: بے گناہ ہونے کے باوجود حضرت یوسف علیہ السلام کو قید کر دیا گیا۔ قید خانے میں بھی آپ نے صبر کا دامن نہیں چھوڑا اور لوگوں کو اللہ کی عبادت کی دعوت دیتے رہے۔ اللہ تعالیٰ کے عطا کردہ علم سے آپ نے دو قیدیوں کے خوابوں کی تعبیر بھی بیان فرمائی۔ Arabic: يَا صَاحِبَيِ السِّجْنِ أَأَرْبَابٌ مُّتَفَرِّقُونَ خَيْرٌ أَمِ اللَّهُ الْوَاحِدُ الْقَهَّارُ Reference: Qur’an 12:39 👑 8. The King’s Dream & Rise to Leadership / بادشاہ کا خواب اور منصب English: When the king of Egypt saw a troubling dream, Yusuf (AS) interpreted it accurately. He explained that seven years of abundance would be followed by seven difficult years of famine. His wisdom and knowledge eventually led to his appointment over the storehouses of Egypt. اردو: جب مصر کے بادشاہ نے ایک پریشان کن خواب دیکھا تو حضرت یوسف علیہ السلام نے اس کی درست تعبیر بیان فرمائی۔ آپ نے بتایا کہ سات سال خوشحالی کے ہوں گے اور اس کے بعد سات سخت قحط کے سال آئیں گے۔ آپ کی حکمت اور علم کی وجہ سے آخرکار آپ کو مصر کے خزانوں اور انتظام کی ذمہ داری دی گئی۔ Arabic: اجْعَلْنِي عَلَىٰ خَزَائِنِ الْأَرْضِ إِنِّي حَفِيظٌ عَلِيمٌ Reference: Qur’an 12:55 🤝 9. Reunion with His Brothers / بھائیوں سے دوبارہ ملاقات English: During the years of famine, Yusuf’s (AS) brothers came to Egypt seeking food. They did not recognize Yusuf (AS), but he recognized them. Allah eventually brought the family together and fulfilled the meaning of Yusuf’s childhood dream. اردو: قحط کے سالوں میں حضرت یوسف علیہ السلام کے بھائی غلہ حاصل کرنے کے لیے مصر آئے۔ وہ حضرت یوسف علیہ السلام کو پہچان نہ سکے، لیکن حضرت یوسف علیہ السلام نے انہیں پہچان لیا۔ اللہ تعالیٰ نے آخرکار پورے خاندان کو دوبارہ ملا دیا اور حضرت یوسف علیہ السلام کے بچپن کے خواب کی تعبیر پوری ہوئی۔ ❤️ 10. Forgiveness of His Brothers / بھائیوں کو معاف کرنا English: When Yusuf (AS) finally revealed his identity to his brothers, he did not seek revenge. Instead, he forgave them and reminded them of Allah’s mercy. His forgiveness became one of the greatest lessons of his life. اردو: جب حضرت یوسف علیہ السلام نے اپنے بھائیوں پر اپنی حقیقت ظاہر کی تو انہوں نے بدلہ لینے کے بجائے انہیں معاف کر دیا۔ آپ نے ان کے لیے اللہ کی رحمت کی امید دلائی۔ آپ کی یہ معافی آپ کی زندگی کے عظیم ترین اسباق میں سے ایک ہے۔ Arabic: لَا تَثْرِيبَ عَلَيْكُمُ الْيَوْمَ ۖ يَغْفِرُ اللَّهُ لَكُمْ Reference: Qur’an 12:92 🌟 11. Fulfillment of the Dream / خواب کی تکمیل English: After many years of trials, Prophet Yusuf (AS) was reunited with his parents and family. His childhood dream was fulfilled, and he recognized that Allah had been guiding his life through every hardship and every stage. اردو: کئی سال کی آزمائشوں کے بعد حضرت یوسف علیہ السلام اپنے والدین اور خاندان سے دوبارہ ملے۔ آپ کا بچپن کا خواب پورا ہوا اور آپ نے محسوس کیا کہ اللہ تعالیٰ ہر آزمائش اور زندگی کے ہر مرحلے میں آپ کی رہنمائی فرماتا رہا۔ Arabic: يَا أَبَتِ هَٰذَا تَأْوِيلُ رُؤْيَايَ مِن قَبْلُ قَدْ جَعَلَهَا رَبِّي حَقًّا Reference: Qur’an 12:100 📖 12. Complete Tafsir Narrative / مکمل تفسیری بیان ENGLISH: Prophet Yusuf (AS) was a symbol of patience, purity, wisdom, forgiveness, and complete trust in Allah. His life moved through many stages: a beloved child, a victim of jealousy, a young man in a foreign land, a prisoner, and finally a trusted leader in Egypt. Throughout every stage, Yusuf (AS) remained faithful to Allah. He refused temptation, remained patient during imprisonment, used the knowledge Allah gave him, and served people with wisdom and justice. When he finally gained authority, he did not use his power for revenge. Instead, he forgave the brothers who had harmed him. His story shows how Allah can bring good outcomes from circumstances that initially appear full of hardship. The story of Yusuf (AS) teaches believers that patience, righteousness, forgiveness, and trust in Allah can transform trials into opportunities for goodness and guidance. URDU: حضرت یوسف علیہ السلام صبر، پاکدامنی، حکمت، معافی اور اللہ پر کامل بھروسے کی عظیم مثال ہیں۔ آپ کی زندگی نے کئی مراحل دیکھے: ایک محبوب بیٹے سے لے کر بھائیوں کے حسد، کنویں کی آزمائش، مصر میں زندگی، قید خانے اور پھر مصر میں ایک اہم منصب تک۔ زندگی کے ہر مرحلے میں حضرت یوسف علیہ السلام اللہ تعالیٰ پر ایمان کے ساتھ قائم رہے۔ آپ نے گناہ سے انکار کیا، قید میں صبر کیا، اللہ کے عطا کردہ علم کو استعمال کیا اور حکمت کے ساتھ لوگوں کی خدمت کی۔ جب اللہ تعالیٰ نے آپ کو اقتدار عطا فرمایا تو آپ نے اپنے بھائیوں سے بدلہ لینے کے بجائے انہیں معاف کر دیا۔ آپ کی زندگی ہمیں سکھاتی ہے کہ اللہ تعالیٰ مشکلات کے اندر بھی خیر کے راستے پیدا فرما سکتا ہے۔ حضرت یوسف علیہ السلام کا واقعہ ہمیں صبر، نیکی، پاکدامنی، معافی اور اللہ پر بھروسے کا عظیم سبق دیتا ہے۔ ARABIC (QUR’ANIC REFERENCES): نَحْنُ نَقُصُّ عَلَيْكَ أَحْسَنَ الْقَصَصِ مَعَاذَ اللَّهِ إِنَّهُ رَبِّي أَحْسَنَ مَثْوَايَ اجْعَلْنِي عَلَىٰ خَزَائِنِ الْأَرْضِ إِنِّي حَفِيظٌ عَلِيمٌ لَا تَثْرِيبَ عَلَيْكُمُ الْيَوْمَ ۖ يَغْفِرُ اللَّهُ لَكُمْ 📖 13. Lessons / اسباق ✔ Patience during hardship ✔ Trust in Allah ✔ Chastity and self-control ✔ Forgiveness ✔ Wisdom and leadership ✔ Never lose hope ✔ Allah’s plan is greater ✔ مشکل میں صبر ✔ اللہ پر بھروسہ ✔ پاکدامنی اور نفس پر قابو ✔ معافی ✔ حکمت اور قیادت ✔ امید نہ چھوڑنا ✔ اللہ کی تدبیر سب سے بہتر ہے 📖 14. Conclusion / نتیجہ Prophet Yusuf (AS) is a timeless example of patience, purity, forgiveness, wisdom, and unwavering trust in Allah. His story reminds believers that hardship can be followed by ease and that Allah’s wisdom is present even when we cannot understand the purpose of a trial. حضرت یوسف علیہ السلام صبر، پاکدامنی، معافی، حکمت اور اللہ پر کامل بھروسے کی ہمیشہ زندہ مثال ہیں۔ آپ کی زندگی ہمیں یاد دلاتی ہے کہ مشکل کے بعد آسانی آ سکتی ہے اور اللہ تعالیٰ کی حکمت ہر آزمائش میں موجود ہوتی ہے، چاہے انسان اس وقت اسے سمجھ نہ سکے۔ 🌿 FundayForum.com FundayForum.com

-
Saylani Welfare International Trust — Saylani I.T Gujranwala
Waqas Dar commented on Waqas Dar's gallery image in Funday Open Gallery
 🚨 Don’t miss the latest job opportunities! 💼 🔥 Check the latest USA, UK & Canada jobs NOW and see if there’s an opportunity that matches your skills. 👉 https://fundayforum.com/forum/220-usa-uk-canada-news-jobs/ ⏰ New opportunities are added regularly — check now and apply before you miss out!
-
Saylani Welfare International Trust — Saylani I.T Gujranwala
Waqas Dar posted a gallery image in Funday Open Gallery
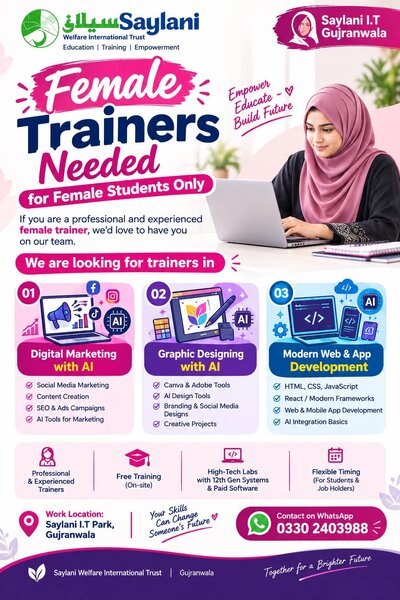
Female Trainers Needed – Saylani I.T Gujranwala Saylani Welfare International Trust — Saylani I.T Gujranwala Education | Training | Empowerment Empower, Educate — Build the Future Saylani I.T Gujranwala is looking for professional and experienced female trainers to join its training team and help female students develop modern, career-focused digital skills. This opportunity is specifically for female trainers who will train female students. We Are Looking For Trainers In: 01. Digital Marketing with AI Social Media Marketing Content Creation SEO & Advertising Campaigns AI Tools for Digital Marketing 02. Graphic Designing with AI Canva & Adobe Tools AI Design Tools Branding & Social Media Designs Creative Design Projects 03. Modern Web & App Development HTML, CSS & JavaScript React & Modern Frameworks Web & Mobile App Development Basics of AI Integration Additional Information Professional & Experienced Trainers Required Free Training – On-site High-Tech Labs with 12th Gen Systems Paid Professional Software Available Flexible Timings Suitable for Students & Job Holders 📍 Work Location Saylani I.T Park, Gujranwala 📱 Contact WhatsApp: 0330 2403988 Your Skills Can Change Someone's Future If you have professional experience in Digital Marketing, Graphic Designing, Web/App Development, AI tools, or related fields and are passionate about teaching, this could be an opportunity to make a meaningful impact. Saylani Welfare International Trust | Gujranwala Together for a Brighter Future 🚨 Don’t miss the latest job opportunities! 💼 🔥 Check the latest USA, UK & Canada jobs NOW and see if there’s an opportunity that matches your skills. 👉 https://fundayforum.com/forum/220-usa-uk-canada-news-jobs/ ⏰ New opportunities are added regularly — check now and apply before you miss out!© Fundayforum.com
-
© Fundayforum.com
-
© Fundayforum.com
-
© Fundayforum.com
-
Top 20 Highest Run Scorers in ODI Cricket History | Most ODI Runs
Waqas Dar posted a gallery image in Funday Open Gallery
 Explore the Top 20 Highest Run Scorers in ODI Cricket History, featuring the legendary batsmen who have accumulated the most runs in One Day International cricket. Discover career statistics, rankings, major records, and the remarkable performances behind the numbers. Visit the full FundayForum topic for the complete list and detailed ODI run records.
© Fundayforum.com
-
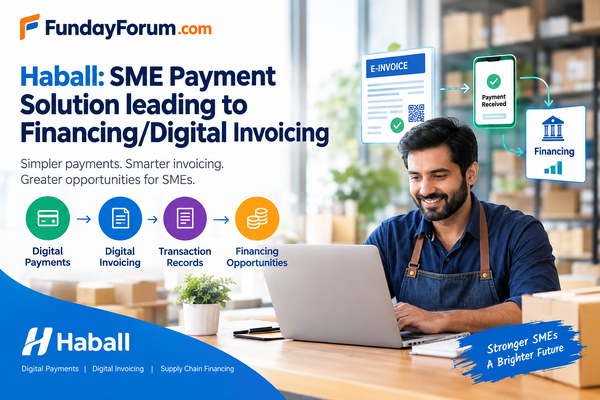
A visual overview of how Haball can connect SME digital payments and e-invoicing with transaction records and supply-chain financing opportunities in Pakistan. Haball: How SME Payments Can Lead to Digital Invoicing and Financing For a small business, getting paid on time can be just as important as making a sale. A distributor may have plenty of customers but still struggle with cash flow because buyers take weeks to settle their invoices. A manufacturer may have confirmed orders but need additional money to purchase raw materials. A retailer may have regular sales but keep most of its records manually. These are everyday problems for small and medium-sized businesses. This is where digital financial services are becoming increasingly important in Pakistan. Haball is one of the fintech companies working in this area, with solutions aimed at digitizing business payments, invoicing and supply-chain financing. The interesting part is that these services are connected. A digital payment is not only a way of transferring money. When it is linked with an invoice and a business transaction, it can also create a useful record of the company's commercial activity. Over time, that information can potentially help an eligible business access financing. In simple terms, the idea can be understood as: Invoice → Payment → Digital Record → Better Cash-Flow Information → Potential Financing What Is Haball? Haball is a Pakistan-based B2B fintech company that focuses on digitalizing financial transactions between businesses. Its services are aimed at different participants in a supply chain, including companies, manufacturers, distributors and retailers. Instead of businesses handling orders, invoices, payments and reconciliation through completely separate manual processes, Haball's approach is to bring more of these activities into a digital environment. This matters because business payments are rarely isolated transactions. When a company sells goods to a distributor, there is normally an order, an invoice, delivery of the goods and eventually a payment. If the payment is delayed, the seller may need working capital to continue operating. A digital platform can connect some of these steps and make the transaction easier to track. Why SME Payments Matter Small and medium-sized businesses often operate on tight cash-flow cycles. Imagine a distributor that purchases goods for PKR 10 million and sells them to retailers for PKR 12 million. On paper, the business has generated a healthy margin. But what happens if the retailers pay after 30 or 60 days? The distributor still has to purchase its next batch of inventory. It also has salaries, transportation, rent and other expenses to cover. The business therefore has money tied up in receivables. This is one reason working capital is so important for SMEs. A digital payment system cannot remove the underlying cash-flow problem, but it can make the movement of money easier to track and reconcile. More importantly, when invoices and payments are digitally recorded, the business can build a clearer history of its transactions. From Paper Invoices to Digital Invoicing In many businesses, invoicing remains a surprisingly manual process. An invoice may be prepared in accounting software, printed, emailed or sent through a messaging application. Someone then has to check whether the customer has paid and update the company's records. When a business handles a small number of invoices, this may be manageable. The problem becomes much bigger when hundreds or thousands of invoices are generated every month. Digital invoicing can simplify this process. Haball's Wasal solution is designed around electronic invoicing and invoice registration. According to Haball, Wasal can integrate with corporate ERP systems and supports invoice registration with the Federal Board of Revenue (FBR), along with invoice validation and QR-code functionality. For a business, the benefit is not simply having a PDF instead of a paper invoice. The bigger benefit is having structured information that can be connected with the payment and accounting process. Why the Invoice Matters An invoice provides evidence that a commercial transaction has taken place. Suppose a Pakistani manufacturer supplies hospital equipment worth PKR 5 million to a distributor. The manufacturer issues an invoice for PKR 5 million. The distributor agrees to pay after 45 days. The manufacturer now has a receivable of PKR 5 million. If the invoice, customer relationship and subsequent payment are recorded digitally, there is a much clearer trail of the transaction. That information can be useful to the business itself. It can also potentially become relevant when the business seeks financing. This is one of the reasons digital invoicing and digital payments can work together rather than being treated as two completely separate technologies. How Financing Enters the Picture The financing opportunity becomes easier to understand when we look at a normal SME cash-flow cycle. A company sells products today. The customer agrees to pay after 30 days. The company needs money tomorrow to purchase more inventory. The company therefore has a timing problem. It has made the sale, but the cash has not yet arrived. Supply-chain financing is designed to address situations like this, depending on the specific financing arrangement. Haball's Wisaaq platform is focused on digital supply-chain financing and connects businesses and financial institutions through a digital process. The basic concept is that eligible commercial transactions can form part of a financing workflow. However, there is an important point that business owners should understand: Using Haball or issuing digital invoices does not automatically mean that an SME will receive financing. Financing remains subject to the relevant bank or financing institution's requirements, credit assessment, documentation, transaction eligibility and other applicable conditions. Digital records can support the assessment; they do not replace it. A Simple Example Consider a distributor that supplies consumer products to 200 retailers. The distributor generates PKR 15 million in invoices every month. Its customers normally pay between 30 and 45 days after receiving their goods. At the same time, the distributor needs to pay suppliers much earlier. This creates a recurring working-capital gap. If the distributor uses digital invoicing and payments, its business records can show: How much it invoices. Which customers are purchasing. How frequently payments are received. How much remains outstanding. How the business's collections change over time. That information does not guarantee financing, but it gives the business a much more organized financial history. If the distributor qualifies for a supply-chain financing product, this transaction history may become part of the financing assessment. This is the real connection between payments and financing. Haball and Supply-Chain Financing Haball's approach is particularly relevant to businesses that operate within established supply chains. A supply chain normally involves several parties: Manufacturer → Distributor → Retailer → Customer Money moves through the same network in the opposite direction. If financial information from these transactions is digitized, there is an opportunity to create a more connected system. The manufacturer can have better information about sales. The distributor can manage payments and invoices more efficiently. The bank or financing institution can potentially receive more structured transaction information. The retailer can receive and settle invoices through digital channels. The result is a more connected financial process. Wisaaq and SME Financing Haball describes Wisaaq as a digital supply-chain financing platform, including an Islamic financing offering. The platform is designed to connect corporate businesses, SMEs and banks and digitize parts of the financing process. This is particularly interesting for Pakistan because many businesses are looking for financing structures that comply with Islamic finance principles. However, businesses should always examine the actual financing agreement, pricing, repayment terms and Shariah structure offered by the relevant financial institution before making a financing decision. A platform can provide the technology, but the actual financing arrangement still needs to be understood on its own terms. The Role of Banks Fintech companies do not necessarily have to replace traditional banks. In fact, one of the more useful models is cooperation between the two. A fintech can provide the technology and digital workflow. A bank can provide the financing. The SME provides the underlying business activity and transaction information. This creates a three-way relationship: SME + Fintech Platform + Financial Institution Haball has announced partnerships with financial institutions in Pakistan in connection with digital supply-chain financing. This type of partnership is important because SMEs ultimately need access not only to technology but also to actual financial products. Digital Records Can Help a Business Even Without Financing There is sometimes too much emphasis on the financing side of fintech. An SME does not need to take a loan for digital payments and invoicing to be useful. Better records alone can make a significant difference. A business owner can more easily identify: Which customers have paid. Which invoices are overdue. How much money is expected next week. Which customers purchase most frequently. How much is being paid to suppliers. Whether sales are increasing or declining. This information can help management make better decisions. For a growing company, knowing its actual cash position can be more valuable than simply knowing its total sales. Digital Payments and Business Transparency Cash has always been an important part of commerce in Pakistan. But cash transactions can be difficult to track at scale. When payments move through digital channels, there is an electronic record of the transaction. This can improve transparency and make reconciliation easier. For example, if a business receives 100 customer payments in a month, manually matching every payment with the correct invoice can take considerable time. A digital workflow can potentially reduce this administrative burden. The result is not only convenience. It can also give the business a more reliable understanding of its financial position. What Does This Mean for a Small Business Owner? For an SME owner, the biggest takeaway is that digitalization should not be viewed simply as "using an online payment service." It is about creating a connected financial process. Instead of: Sale → Paper Invoice → Manual Entry → Bank Payment → Manual Reconciliation the process can move toward: Sale → Digital Invoice → Digital Payment → Digital Record → Reconciliation And if the business needs working capital: Digital Transaction History → Financing Assessment → Potential Supply-Chain Finance That is a much broader proposition. What SMEs Should Check Before Choosing a Financing Solution Businesses should not choose a financial service simply because it promises fast financing. Before entering into any arrangement, an SME should understand: What financing amount is available? What is the total cost of financing? What fees are charged? What is the repayment period? Is collateral or a guarantee required? Which financial institution provides the financing? What invoices or transactions qualify? What documentation is required? What happens if a customer does not pay? What are the applicable terms and conditions? These questions are important because financing should solve a cash-flow problem without creating a larger financial burden. The Importance of FBR E-Invoicing Electronic invoicing is also becoming increasingly relevant because Pakistan's tax system is moving toward greater digitalization. Businesses need to understand their applicable FBR requirements and whether they fall within the relevant e-invoicing rules. Haball's Wasal solution is positioned around electronic invoicing and integration with FBR requirements. For businesses that need to maintain compliant digital records, this type of technology can potentially reduce manual processes. However, companies should always verify their specific tax obligations with FBR or a qualified tax professional because requirements can differ depending on the taxpayer and nature of business. Is Haball Only Useful for Large Companies? No. Although large companies can benefit significantly from supply-chain digitization, the SME side is an important part of the model. A large company may have an established ERP system and finance department. A smaller distributor may not have the same level of infrastructure. Digital platforms can potentially give smaller businesses access to tools that would otherwise require significant investment in technology and administrative resources. The actual availability of a particular product, however, depends on Haball's current services, participating partners and the business's eligibility. The Bigger Opportunity The bigger story behind Haball is the gradual movement from transaction-based finance to data-supported business finance. In the traditional model, a bank may see a company's financial position mainly through periodic statements and documents. In a more digital model, business activity can generate information continuously. Invoices show sales. Payments show collections. Transaction history shows patterns. Supply-chain relationships provide additional context. This does not eliminate the need for traditional financial analysis, but it can potentially give lenders a more complete picture of an SME. For small businesses that have historically struggled to demonstrate their financial strength, that can be meaningful. Final Thoughts Haball's SME payment solution is best understood as part of a wider shift in the way businesses manage money. The payment itself is only one piece of the puzzle. When payments are connected with invoices, accounting records and supply-chain activity, they can create a much clearer picture of how a business operates. Digital invoicing can make transactions easier to document. Digital payments can make collections easier to track. Structured transaction records can improve financial visibility. And, for eligible businesses, that information can potentially support access to supply-chain financing. The journey can therefore be summarized simply: Business Sale → Digital Invoice → Digital Payment → Transaction Record → Better Financial Visibility → Potential Financing For Pakistan's SMEs, this transition has practical significance. A business that keeps accurate digital records is in a stronger position to understand its own cash flow, manage customers and suppliers, meet applicable compliance requirements and demonstrate its commercial activity to potential financial partners. Haball is one example of how fintech is attempting to connect these different parts of the business cycle. The real value will ultimately depend on how effectively SMEs adopt these tools, how well financial institutions use the resulting information, and whether digital financing products remain transparent, affordable and suitable for the businesses using them. For an SME owner, the goal should not simply be to "go digital." The goal should be to build a better documented, better managed and financially visible business.
-
Looking for a complete guide on how to register with GCCI in Gujranwala? The Gujranwala Chamber of Commerce & Industry (GCCI) membership process involves checking your business eligibility, preparing the required legal and tax documents, selecting the appropriate membership class, completing the GCCI membership application form, submitting the documents for verification and paying the applicable membership fee. This GCCI registration guide 2026 explains the complete process in simple steps for sole proprietors, partnerships, AOPs, private limited companies, manufacturers, traders, importers, exporters and service providers. You will also find the latest GCCI membership fees, required documents, Associate and Corporate membership information, registration flow chart, renewal requirements, common mistakes and frequently asked questions. If you are planning to obtain GCCI membership in Gujranwala, preparing your documents correctly before submitting your application can help make the registration process smoother and reduce delays caused by incomplete or inconsistent information. ### FAQ Section Frequently Asked Questions About GCCI Registration 1. What is GCCI? GCCI stands for Gujranwala Chamber of Commerce & Industry. It is a Chamber representing the business and industrial community of Gujranwala and supporting commercial, industrial and trade-related activities. 2. Who can apply for GCCI membership? Eligible businesses operating within the GCCI jurisdiction can apply. This may include sole proprietorships, partnerships, AOPs, private limited companies, limited companies, manufacturers, traders, importers, exporters and service providers, subject to the applicable GCCI requirements. 3. What documents are required for GCCI membership? The required documents depend on your business structure. Common documents include the GCCI membership application form, CNIC, photograph, NTN, sales tax registration where applicable, business registration documents, business address and information about your business nature and products or services. 4. What is the difference between Associate and Corporate GCCI membership? GCCI has Associate and Corporate membership classes. Associate membership is generally for businesses that do not qualify for Corporate Class, while Corporate membership is available to businesses meeting GCCI's specific Corporate Class criteria. 5. How much does GCCI membership cost? The membership fee depends on the membership class and the period in which the application is submitted. GCCI's published fee schedule effective from 16 December 2025 lists different fees for Associate and Corporate membership. Applicants should confirm the current fee with GCCI before making payment. 6. Do I need NTN for GCCI membership? Yes. NTN and other relevant tax-registration information form an important part of the GCCI membership documentation. Additional tax documents may be required depending on your business structure and activities. 7. Is Sales Tax Registration required for GCCI membership? Sales Tax Registration is required where applicable. The exact requirement can depend on the nature of the business and the membership class. Businesses should confirm their specific requirements with GCCI before applying. 8. Do I need a proposer and seconder for GCCI membership? GCCI's published membership requirements provide for a new membership application to be proposed and seconded by existing members where applicable. Applicants should confirm the current requirements with the GCCI Membership Department. 9. How do I apply for GCCI membership? The general process is: Check eligibility → Prepare documents → Select membership class → Complete application form → Arrange proposer/seconder where applicable → Submit application → GCCI verification → Pay fee → Approval → Receive membership certificate and card. 10. Can I register for GCCI membership online? GCCI provides an online registration section on its website, but the current website indicates that the online registration facility is still listed as “Coming Soon.” Therefore, applicants should confirm the current submission procedure directly with GCCI before relying on online registration. 11. How long does GCCI membership registration take? The processing time can vary depending on the completeness of the application, verification requirements and any deficiencies in the submitted documents. To avoid unnecessary delays, submit a complete and accurate application and respond promptly if GCCI requests additional information. 12. What happens if my GCCI application has missing documents? GCCI may require the applicant to provide missing or corrected documents before the application can be completed. It is therefore recommended to prepare a complete document file and ensure that the information matches your official business and tax records. 13. Do manufacturers need GCCI membership? Manufacturers operating within the applicable GCCI jurisdiction can apply for membership if they meet the relevant requirements. Manufacturers should provide accurate information about their manufacturing activities and products. 14. Can exporters and importers become GCCI members? Yes, eligible importers and exporters can apply for GCCI membership. Applicants should clearly mention their import or export activities and provide the relevant business and tax documentation. 15. When does GCCI membership need to be renewed? GCCI membership is subject to annual renewal according to the Chamber's applicable rules. GCCI's published membership information states that the subscription deadline is 31 March each year. 16. What are the benefits of GCCI membership? GCCI membership can provide businesses with opportunities for networking, business representation, trade-related activities, seminars, business events, business information and other Chamber-related services. 17. How can I verify my GCCI membership? GCCI provides a members-verification facility through which membership information can be checked using the relevant membership details. 18. Where can I get the GCCI membership form? The GCCI website provides a Membership Forms section where applicants can access the relevant membership forms and information. Always use the latest version of the form available from GCCI. 19. What should I write as my business nature in the GCCI application? You should provide a clear and accurate description of your actual business activity. For example, instead of simply writing “General Trading,” you can specify the products or services you trade, manufacture, import or export. 20. What should I do before visiting GCCI for registration? Prepare your complete application file, including your GCCI form, CNIC, photograph, NTN, sales tax documents where applicable, business registration documents, business address details, business nature and any required proposer/seconder information. Also confirm the latest GCCI fee and submission requirements before visiting. GCCI Registration – Quick Answer If you want to register with GCCI, the process can be summarized as: 1. Check Eligibility ↓ 2. Prepare Legal & Tax Documents ↓ 3. Select Associate or Corporate Class ↓ 4. Complete GCCI Membership Form ↓ 5. Arrange Proposer & Seconder Where Applicable ↓ 6. Submit Application ↓ 7. GCCI Verification ↓ 8. Pay Applicable Fee ↓ 9. Membership Approval ↓ 10. Receive GCCI Certificate & Membership Card Final Tip: GCCI requirements, forms and fees can change. Always confirm the latest information directly with the Gujranwala Chamber of Commerce & Industry before submitting your application or paying any fee. Related Business, Import, Export & Tax Guides If you are registering with GCCI and want to learn more about export procedures, import/export compliance, tax requirements and trade facilitation in Pakistan, these related guides may also be useful: 🔹 GCCI Membership Registration How to Register with GCCI in 2026 – Complete Membership Guide, Documents, Fees & Registration Process 🔹 Export Facilitation Scheme (EFS) 2026 Export Facilitation Scheme (EFS) 2026 – Complete Guide for Pakistani Exporters & SMEs 🔹 Export Taxes in Pakistan Complete Guide to Export Taxes in Pakistan – FBR Rules & Compliance 🔹 Import & Export Consultancy Import & Export Consultancy in Pakistan 2026 – PSW, WEBOC, Customs & Trade Documentation For Pakistani businesses, manufacturers, exporters and importers: GCCI membership can be an important part of building your business network and accessing trade-related opportunities. Understanding tax, customs and export-facilitation requirements can further help businesses prepare for local and international trade.
-
Export Facilitation Scheme (EFS) 2026: What Pakistani Exporters & SMEs Need to Know Short Description: Learn about Pakistan's Export Facilitation Scheme (EFS) 2026, including the new 18-month input utilisation period, zero-duty imports, SME benefits, reconciliation, eligibility, compliance and common mistakes. Introduction For Pakistani manufacturers and exporters, the cost of raw materials, imported inputs, taxes and working capital can have a major impact on international competitiveness. The Export Facilitation Scheme (EFS) was introduced to make it easier for eligible exporters to obtain inputs needed for manufacturing exportable goods without the normal upfront burden of duties and taxes, subject to the scheme's conditions and compliance requirements. The scheme is particularly relevant to: Manufacturers-cum-exporters Commercial exporters Indirect exporters Common Export Houses Vendors International toll manufacturers Small and medium-sized enterprises (SMEs) The original EFS 2021 framework was designed to replace older export schemes and provide a more automated and streamlined system through WeBOC and the Pakistan Single Window (PSW). FBR's original announcement stated that eligible imported inputs could be obtained without duty and taxes, while qualifying local supplies to authorized users could be zero-rated. In 2026, the scheme received an important policy change. The major EFS 2026 development The Government of Pakistan increased the input utilisation period from 9 months to 18 months. This means eligible exporters now have more time to use imported inputs under EFS for the production of goods that are subsequently exported. The government stated that the change should reduce costs and particularly benefit SME exporters. It also announced a possible additional six-month extension on a case-by-case basis. 1. What Is the Export Facilitation Scheme (EFS)? The Export Facilitation Scheme 2021 is a customs and export facilitation framework designed to provide authorized exporters with access to inputs for export production under preferential customs/tax treatment. Under the original framework, the scheme covered inputs such as: Raw materials Components Spare parts Equipment Plant and machinery Other eligible goods used in the manufacture of exportable products FBR described the scheme as covering manufacturers-cum-exporters, commercial exporters, indirect exporters, common export houses, vendors and international toll manufacturers. The basic concept is: Import/procure eligible inputs → manufacture/process → export finished goods rather than requiring the exporter to bear the normal upfront duty/tax burden on qualifying inputs and then rely on separate refund or drawback mechanisms. 2. Why Was EFS Introduced? Pakistan has historically faced several challenges affecting export competitiveness. These include: High input costs Working-capital constraints Delayed refunds Complex export procedures Upfront taxation Difficulty accessing imported production inputs Compliance costs Liquidity pressure on SMEs The EFS was designed to address some of these problems. FBR's original announcement described the scheme as a mechanism intended to reduce the cost of doing business and tax compliance, reduce exporters' liquidity problems and encourage new entrants and SMEs. 3. The Big EFS Change in 2026 The most important change for exporters in 2026 is the extension of the input utilisation period. Previous position Under the revised policy framework, exporters had a 9-month utilisation period for relevant EFS inputs. New position The Government announced that this period has been increased to: 18 Months This gives exporters significantly more time to consume/use the eligible inputs in export production. The government announced the change on 19 March 2026, explaining that the longer period would reduce exporters' costs and particularly assist SMEs. 4. Why Is the 18-Month Period Important? Consider a small Pakistani manufacturer that imports raw material under EFS. Suppose the business imports: Rs. 50 million of eligible production inputs. Previously, the shorter utilisation period could create pressure to: Produce quickly Secure export orders quickly Consume the inputs within the prescribed period Complete the necessary export process For SMEs with seasonal products or fluctuating international orders, this could create significant working-capital and inventory pressure. With the utilisation period extended to 18 months, the exporter has more time to align: Input purchase → production → customer order → shipment → export This can be particularly valuable where production cycles are long or export orders are seasonal. 5. Can the 18-Month Period Be Extended Further? Yes, according to the government's March 2026 announcement. An additional six-month extension beyond the 18-month utilisation period may be considered by a committee on a case-by-case basis. This should not be interpreted as an automatic 24-month period for every exporter. The important distinction is: 18 months = revised standard utilisation period while additional 6 months = possible case-by-case extension Therefore, exporters should not assume that they automatically receive 24 months. 6. Who Can Benefit From EFS? The EFS framework is designed for various categories of export-oriented businesses. These include: 1. Manufacturers-cum-Exporters Businesses that manufacture products and export them directly. 2. Commercial Exporters Businesses that source eligible goods/inputs and export qualifying products. 3. Indirect Exporters Businesses supplying inputs or products to authorized exporters in the export supply chain. 4. Common Export Houses A mechanism that can help facilitate access to inputs for authorized exporters, including SMEs. 5. Vendors Businesses supplying inputs/products to exporters under the scheme. 6. International Toll Manufacturers Businesses involved in manufacturing arrangements where goods are produced in Pakistan for international customers/principals. FBR's original EFS announcement specifically identified these categories. 7. What Inputs Can Be Covered? The EFS framework can cover eligible inputs required for export production. Depending on authorization and applicable rules, these can include: Raw materials Components Parts Consumables Packaging-related inputs Machinery Plant Equipment Other approved inputs However, an exporter should not assume that every imported item automatically qualifies. The input must fall within the applicable EFS authorization and production requirements. The original EFS framework provides for authorization of inputs by the relevant customs/IOCO authorities. 8. What Does "Duty-Free" Mean Under EFS? A common misunderstanding is: "EFS means I can import anything without paying tax." That is incorrect. The benefit applies to eligible inputs under the scheme and subject to its conditions. The government specifically described the 2026 change as allowing exporters to avail zero duty and import-stage taxes for imported inputs, provided the inputs are used within the applicable 18-month utilisation period. Therefore: EFS benefit ≠ unrestricted duty-free importing Instead: Authorized exporter + authorized inputs + prescribed conditions + export utilisation = EFS benefit 9. What Happens to Locally Procured Inputs? The original EFS framework also provided for qualifying local supplies of inputs to authorized users to receive zero-rated treatment, subject to the applicable conditions. This is important for Pakistani SMEs because an exporter does not necessarily have to import every input itself. An export supply chain can look like: Local Supplier ↓ EFS Authorized Exporter ↓ Manufacturing ↓ Foreign Buyer This can allow smaller businesses to participate in the export supply chain as vendors. FBR's original EFS announcement specifically highlighted local supplies to authorized users and the participation of vendors in the scheme. 10. How EFS Can Help SMEs The EFS can be particularly important for SMEs because smaller exporters often face greater working-capital constraints. Traditional problem An SME may need to: Import raw material. Pay applicable taxes/duties. Manufacture goods. Wait for the export order. Export. Wait for payment. Potentially deal with refund/drawback processes. This can tie up substantial capital. EFS model An eligible exporter can potentially obtain authorized inputs under EFS without the same upfront duty/tax burden, subject to the scheme's conditions. This can improve: Cash flow Production planning Export competitiveness Working capital Pricing flexibility International market access FBR originally stated that the scheme was expected to reduce liquidity problems and encourage new entrants and SMEs. 11. Example: How EFS Could Help a Small Manufacturer Imagine a Gujranwala manufacturer producing sports goods. The company receives a large international order. It needs: Synthetic material Leather Components Packaging Machinery parts The company may need significant working capital before receiving the foreign buyer's payment. If the relevant inputs qualify under EFS and the company is properly authorized, the scheme can reduce the upfront customs/tax burden associated with those inputs. The manufacturer can then: Import eligible inputs ↓ Manufacture ↓ Export ↓ Realize export proceeds ↓ Complete EFS reconciliation This can make the transaction financially easier to manage. 12. The 18-Month Rule — Simple Example Suppose an exporter imports eligible EFS inputs on: 1 September 2026 Under the announced 18-month utilisation period, the relevant inputs would generally need to be utilized within the prescribed period, subject to the exact applicable rules and authorization. The exporter should therefore maintain a clear timeline. Activity Example Input import September 2026 Production planning September–October 2026 Manufacturing October 2026 onward Export shipments As orders are completed Reconciliation According to applicable schedule Utilisation deadline Track carefully against the 18-month period Do not wait until the final months to reconcile your EFS inputs. 13. EFS Reconciliation — Why It Matters The EFS is not simply a tax-free import facility. It is a controlled export facilitation mechanism. The exporter must be able to demonstrate: What was imported? ↓ How much was consumed? ↓ What was produced? ↓ What was exported? ↓ What remains in stock? This is why reconciliation is one of the most important EFS compliance requirements. The government announced in March 2026 that a six-monthly reconciliation statement would help safeguard the scheme from abuse. 14. What Should an SME Track? An EFS user should maintain an input-output register. For example: Item Quantity Imported raw material 10,000 kg Used in production 7,500 kg Exported production Equivalent quantity Production wastage 500 kg Closing balance 2,000 kg The actual calculation will depend on the product, approved input-output ratios and applicable EFS requirements. The purpose is to create a clear audit trail. 15. Input-Output Ratio One of the most important concepts for manufacturers is the relationship between: Input and Exported Output For example: 1,000 kg raw material might produce: 850 kg finished product with the balance accounted for as: Waste Process loss By-product Scrap Other permissible categories The exporter should not simply invent an input-output ratio. It should follow the authorized production/input-output parameters applicable to the EFS authorization. 16. Why Inventory Management Is Critical Suppose an exporter receives: 100 tons of imported raw material under EFS. The exporter cannot treat the material as ordinary unrestricted stock. It should maintain records showing: Import date GD number Quantity Value PCT/HS classification Production consumption Remaining stock Exported output Wastage/scrap Relevant reconciliation Poor inventory records can turn an otherwise legitimate EFS benefit into a serious compliance problem. 17. EFS Is Not Permission to Sell Duty-Free Inputs Locally This is one of the most important rules exporters must understand. The EFS facility exists to support export production. An exporter cannot simply import goods under EFS and then sell them in the domestic market outside the permitted framework. A June 2026 government announcement described a major enforcement case involving alleged misuse of EFS where duty-free imported cotton was allegedly disposed of in the local market. The reported case involved goods valued at approximately Rs. 471 million and alleged duty/tax exposure of Rs. 116.5 million. The case illustrates the seriousness of EFS compliance. Practical lesson Never treat EFS inventory as normal domestic inventory. 18. FBR and Customs Are Increasing Post-Clearance Oversight The original EFS model was designed around automation and post-clearance compliance. FBR stated that the scheme would operate through WeBOC and PSW, with regulators integrated into the system, while emphasizing post-clearance compliance checks and audits. This means an exporter should not think: "Customs cleared my import, so the matter is finished." The import is only one part of the process. The exporter may still need to demonstrate: Consumption Production Export Reconciliation Inventory control Compliance with authorization 19. WeBOC and Pakistan Single Window Digital systems are an important part of the EFS framework. The original scheme was designed to operate through: WeBOC Pakistan Customs' electronic clearance environment. PSW Pakistan Single Window, designed to facilitate trade-related regulatory interactions. FBR stated that EFS users and relevant regulators would be integrated through WeBOC and PSW. For exporters, this means that digital records and system data are increasingly important. 20. Automatic Replenishment of Security Deposit Another improvement announced in March 2026 concerns the automatic replenishment of the security deposit to the extent of goods consumed and exported. According to the government, this is intended to save exporters time. For an exporter repeatedly using EFS, this can be operationally significant because it may reduce delays associated with maintaining the required security position. 21. Right of Appeal The government also announced that EFS users have been given a right of appeal to the Chief Collector against orders of the Regulatory Collector. This provides an additional mechanism for exporters dealing with regulatory decisions under the scheme. However, businesses should still focus primarily on prevention: Correct authorization + correct records + correct reconciliation = fewer disputes. 22. EFS and Export Refunds One major conceptual advantage of EFS is that it can reduce reliance on refund mechanisms for qualifying inputs. FBR's original announcement stated that the scheme was intended to reduce liquidity problems by eliminating the need for sales-tax refunds and duty drawback for users of the scheme in the relevant circumstances. This can be important for SMEs. Instead of: Pay tax → export → wait for refund the EFS model can provide qualifying inputs under the scheme without the same upfront burden. That can improve cash flow. 23. EFS vs Traditional Export Refund Model Feature Traditional approach EFS Input purchase/import Tax/duty may be paid upfront Eligible inputs can receive EFS treatment Working capital Higher Potentially lower Refund dependency May be significant Can be reduced Compliance Tax/refund records EFS authorization + reconciliation Inventory control Normal Strict tracking required Export requirement Yes Yes Post-clearance scrutiny Possible Important SME benefit Depends on refund cycle Potentially significant The exact treatment depends on the exporter, product, authorization and applicable rules. 24. What Documents Should an EFS User Maintain? An EFS exporter should maintain a complete file covering: Business records NTN Sales-tax registration where applicable Company/firm registration Bank details Exporter profile EFS records EFS authorization Approved inputs Approved quantities Input-output ratios Security documentation Reconciliation statements Relevant correspondence Import records GDs Commercial invoices Packing lists Bill of Lading/AWB Customs records Production records Material issue notes Production sheets Stock registers Consumption records Wastage records Finished goods records Export records Export invoices Packing lists GDs Shipping documents Certificates Bank realization records 25. EFS Compliance Checklist for SMEs Before using EFS: Confirm business eligibility Check exporter registration requirements Obtain required authorization Identify eligible inputs Confirm input-output ratios Understand security requirements Establish inventory controls Establish production records Set up export documentation Understand reconciliation requirements After receiving inputs: Record each GD Record quantity Record value Track consumption Track production Track wastage Track finished goods Track exports Reconcile regularly Before the utilisation deadline: Review unused inventory Identify pending production Identify pending export orders Reconcile consumed quantities Resolve discrepancies Check whether an extension is required Maintain supporting evidence 26. Common EFS Mistakes Mistake 1 — Importing More Than Needed Do not use EFS as a way to accumulate unnecessary inventory. Mistake 2 — Poor Stock Records If you cannot explain where the imported material went, your compliance position becomes weak. Mistake 3 — Mixing EFS and Domestic Stock Keep EFS-controlled inputs clearly identifiable. Mistake 4 — Ignoring the Utilisation Deadline The 18-month period should be monitored from the beginning. Mistake 5 — Assuming the 6-Month Extension Is Automatic It is not. The government's announcement describes an additional six-month extension as something that may be considered case by case. Mistake 6 — Selling EFS Inputs Locally This can create serious customs and tax consequences. The 2026 enforcement action demonstrates that misuse can result in criminal proceedings. Mistake 7 — Ignoring Reconciliation Reconciliation should be treated as a regular management function, not a last-minute exercise. 27. How SMEs Can Prepare for an EFS Audit A simple audit test is: Question 1 Show me the import. Answer: GD + invoice + shipping documents. Question 2 Where did the input go? Answer: Inventory/production records. Question 3 What was produced? Answer: Production records. Question 4 Where was the finished product sold? Answer: Export invoice + export GD. Question 5 Where did the money go? Answer: Bank realization. Question 6 Can the entire chain be reconciled? Answer: Yes. If an SME can answer these questions confidently, it has a much stronger compliance system. 28. EFS for Different Industries The scheme can be relevant to many export-oriented sectors, subject to eligibility and applicable authorization. Examples include: Textile & Garments Fabric Yarn Accessories Dyes Components Sports Goods Leather Rubber Components Accessories Packaging Surgical Instruments Steel Components Specialized materials Furniture Wood Hardware Fittings Finishing materials Leather Goods Leather Chemicals Accessories Packaging Engineering Goods Metals Components Machinery inputs Parts Food Processing Eligible ingredients Packaging Processing inputs The exact EFS treatment should always be checked for the specific product and input. 29. Why EFS Matters for Gujranwala SMEs Gujranwala has a substantial manufacturing and industrial base, including businesses involved in: Engineering Sanitaryware Ceramics Home appliances Metal products Furniture Sports-related supply chains Food products Light engineering Trading and manufacturing For these businesses, export growth often depends on controlling production costs. EFS can therefore be an important subject for SMEs considering their first export order or trying to increase existing exports. 30. EFS and New Exporters A business that has never exported before should not assume that EFS is simply an import concession. The exporter should first establish: Product ↓ Foreign buyer ↓ Export market ↓ PCT/HS classification ↓ Input requirement ↓ Production process ↓ Input-output ratio ↓ EFS eligibility ↓ Authorization ↓ Import/procurement ↓ Manufacturing ↓ Export ↓ Reconciliation This approach reduces the risk of importing inputs before understanding the compliance requirements. 31. EFS and Working Capital Working capital is often one of the biggest barriers for SMEs. Consider a business that needs: Rs. 20 million to purchase production inputs. If significant taxes and duties must be paid upfront, the actual financing requirement can increase. An eligible EFS arrangement may reduce the upfront burden on qualifying inputs. That can allow the same SME to use its capital for: Wages Electricity Production Packaging Freight Marketing New export orders This is one reason the government has specifically highlighted SMEs when discussing the EFS reforms. 32. EFS Does Not Remove All Business Costs Exporters should also understand what EFS does not automatically eliminate. Businesses may still have costs relating to: Freight Insurance Banking Production Labour Energy Packaging Port charges Documentation Compliance Certification Testing Marketing Buyer requirements EFS is therefore one component of an export strategy—not a complete solution to export costs. 33. EFS and Export Competitiveness Pakistan competes with manufacturers from countries where exporters may have efficient supply chains and relatively low input costs. Reducing the tax/duty burden on eligible export inputs can help Pakistani exporters compete on: Price Lower input burden can improve pricing flexibility. Cash flow Less capital tied up in taxes can support production. Delivery Better inventory planning can help meet international orders. Expansion SMEs can potentially take larger export orders. Diversification Businesses may explore additional international markets. The government has continued to emphasize export diversification, new markets and stronger participation by SMEs in Pakistan's export growth strategy. 34. 2026 EFS Quick Facts Item 2026 Position Scheme Export Facilitation Scheme 2021 Major 2026 change Input utilisation period increased Previous utilisation period 9 months Current announced utilisation period 18 months Additional extension Up to 6 months may be considered case-by-case Target users Exporters, manufacturers, vendors, SMEs and other eligible users Import benefit Eligible inputs can receive zero-duty/import-stage tax treatment subject to conditions Local input treatment Qualifying supplies can receive zero-rating subject to applicable rules Reconciliation Six-monthly reconciliation announced as a safeguard Security Automatic replenishment announced to extent of consumed/exported goods Appeal Right of appeal to Chief Collector announced Technology WeBOC/PSW-based framework Main objective Reduce export costs and improve competitiveness The key 2026 changes above are based on the government's March 2026 announcement. 35. EFS Compliance Formula for SMEs An easy way to remember EFS compliance is: AUTHORIZE → IMPORT → TRACK → PRODUCE → EXPORT → RECONCILE AUTHORIZE Obtain the appropriate EFS authorization. IMPORT Bring in only eligible inputs. TRACK Maintain inventory and documentation. PRODUCE Use the inputs for authorized production. EXPORT Export the resulting goods as required. RECONCILE Match inputs with production and exports. 36. Final Advice for Pakistani Exporters The 2026 EFS reforms provide a potentially valuable opportunity for Pakistani exporters, especially SMEs. The extension from 9 months to 18 months gives eligible businesses considerably more time to utilize inputs under the scheme. The government has also introduced additional measures involving reconciliation, security-deposit replenishment and appeals. But the benefit comes with responsibility. An exporter should never think: "EFS means duty-free imports, so I can import whatever I want." The correct approach is: "EFS allows eligible exporters to obtain eligible inputs under a controlled export-production framework, subject to authorization, utilization, documentation and reconciliation." The 2026 enforcement action involving alleged misuse of EFS is a clear reminder that the government is paying attention to how duty-free inputs are used. For SMEs, the best strategy is therefore to build compliance into the business from day one. 37. Frequently Asked Questions What is EFS in Pakistan? EFS stands for Export Facilitation Scheme. It is an export-oriented customs facilitation framework allowing authorized users to obtain eligible inputs under preferential duty/tax treatment subject to the scheme's conditions. What changed in EFS in 2026? The government increased the input utilisation period from 9 months to 18 months. Can the 18 months be extended? An additional six-month extension may be considered by the relevant committee on a case-by-case basis. It is not an automatic extension. Does EFS mean all imports are duty-free? No. Only eligible inputs covered by the applicable authorization and scheme conditions receive the relevant treatment. Can SMEs use EFS? Yes. SMEs are specifically among the businesses that the government has highlighted as potential beneficiaries of the extended utilisation period. Can EFS inputs be sold in Pakistan? They should not be treated as unrestricted domestic inventory. Unauthorized diversion or disposal can result in serious customs and tax consequences. Does EFS eliminate the need for documentation? No. Documentation and reconciliation are essential. What systems are used for EFS? The EFS framework was designed around electronic systems including WeBOC and Pakistan Single Window (PSW). What is the biggest benefit for an SME? Potentially lower upfront input costs and improved working capital, allowing the business to become more competitive in international markets. Is EFS suitable for every exporter? Not necessarily. Eligibility, authorization, product, inputs, production process and other conditions must be examined before relying on the scheme. 38. EFS 2026 Checklist for a New Pakistani Exporter Before applying or using EFS, ask: What product am I exporting? What is its correct PCT/HS classification? Who is my foreign buyer? What inputs do I need? Which inputs are eligible? What is my production process? What is my authorized input-output ratio? What records will I maintain? How will I track EFS inventory? When will the inputs be utilized? When will the goods be exported? How will I reconcile the shipment? What happens if I cannot utilize the inputs within 18 months? Do I need to request an extension? Is my accounting system ready for an EFS audit? If an SME cannot answer these questions, it should obtain professional guidance before importing significant quantities of inputs under the scheme. Conclusion The Export Facilitation Scheme (EFS) 2026 represents an important opportunity for Pakistani manufacturers and exporters. The most significant recent change is the extension of the input utilisation period from 9 months to 18 months, with the possibility of a further six-month extension on a case-by-case basis. The government has also announced measures relating to reconciliation, security-deposit replenishment and appeals. For SMEs, the biggest potential advantages are: Lower upfront input burden Improved working capital Better production planning Reduced reliance on refund mechanisms Greater export competitiveness More flexibility in managing international orders However, EFS is not a free-import scheme. It is a controlled export facilitation mechanism. The successful EFS exporter is one who can demonstrate a complete chain: Authorized Input → Import → Inventory → Production → Export → Bank/Commercial Records → Reconciliation Businesses that maintain accurate records and comply with the scheme can use EFS as an important tool for expanding their international business. For Pakistani SMEs considering exports in 2026, understanding EFS should be considered part of the basic export-readiness checklist. Official References Federal Board of Revenue — Export Facilitation Scheme and operative export-related SROs. Government of Pakistan — March 19, 2026 announcement on the EFS 18-month utilisation period and related reforms. Government of Pakistan — June 2026 EFS enforcement action highlighting the importance of compliance. FBR/Ministry of Information — Original EFS 2021 framework and its objectives.
-
Understanding Taxes on Exports in Pakistan Complete Guide to FBR Rules, Zero-Rating, Export Documentation & Compliance — 2026 Short Description: Learn how export taxation works in Pakistan, including FBR income tax, sales tax zero-rating, export proceeds, refunds, customs requirements, documentation and practical compliance guidance for exporters and SMEs. Important: This guide is prepared for educational and training purposes. Export taxation can depend on the product, exporter status, transaction structure, export destination and applicable notifications/SROs. Specific transactions should be checked against the law and current FBR/Customs requirements before filing. 1. Introduction Exporting from Pakistan is not simply a matter of finding a foreign buyer, preparing an invoice and sending goods overseas. A successful exporter must understand the tax, customs, banking, documentation and regulatory framework surrounding the transaction. For an SME, a mistake in one area can create problems somewhere else. For example: The invoice may show one product description while the Goods Declaration shows another. The HS/PCT classification may not match the actual product. Input sales tax may not be properly documented. Export proceeds may not be properly reconciled with the export declaration. The exporter may incorrectly assume that every export-related transaction is automatically zero-rated. Income-tax treatment may be misunderstood because the exporter is still thinking in terms of the old final-tax regime. This last point is particularly important. The FBR has confirmed that the Finance Act 2024 changed the tax regime applicable to exporters from a final-tax regime to a minimum-tax regime. FBR subsequently clarified in January 2026 that this change must be reflected in the relevant income-tax returns. (Federal Board of Revenue) Therefore, Pakistani exporters need to look at exports as a complete compliance chain, rather than treating export tax as a single percentage. 2. What Is an Export Tax? The expression "export tax" can be misleading. An exporter may encounter several different taxes, duties, levies or tax mechanisms, including: Area What it relates to Income Tax Tax treatment of export proceeds/income Sales Tax Treatment of exported goods and related input tax Customs Duty Mainly relevant to imported inputs and customs treatment Regulatory Duties Product-specific where applicable Export Development-related charges Subject to applicable law/notifications Withholding/advance tax Collection at source on export proceeds where applicable Sales Tax Refund Recovery of eligible input tax connected with zero-rated exports Customs concessions Export schemes and duty-relief mechanisms So the correct question is not: "How much tax do I pay on exports?" The better question is: "What taxes apply to my particular export transaction, and what documentation is required to establish the correct treatment?" 3. The Three Major Tax Areas an Exporter Should Understand For most goods exporters, the basic framework can be divided into three major areas: A. Income Tax This deals with the taxation of income/export proceeds under the Income Tax Ordinance, 2001. B. Sales Tax Exports are generally treated under the zero-rating framework rather than ordinary domestic consumption taxation. C. Customs Customs controls the movement of goods across Pakistan's borders and determines classification, declarations and applicable customs procedures. The FBR currently publishes the Pakistan Customs Tariff for FY 2026–27 and the updated Fifth Schedule to the Customs Act, 1969, so exporters should verify their product's current classification and applicable concessions rather than relying on an old tariff. (Federal Board of Revenue) 4. Income Tax on Export Proceeds This is one of the most important changes exporters need to understand. Historically, many exporters were familiar with the concept that tax deducted from export proceeds represented a final tax. That position changed. The FBR's official explanation confirms that the Finance Act 2024 changed the treatment of tax collected under section 154 from a final-tax regime to a minimum-tax regime. (FBR) This means exporters should not automatically treat the tax collected on export proceeds as the complete and final settlement of their income-tax position. Why this matters An exporter should maintain proper records of: Export turnover Export proceeds Direct costs Manufacturing costs Trading costs Administrative expenses Bank charges Freight Insurance Commission Other allowable business expenses Tax deducted/collected Tax return declarations The exporter should then correctly reflect the transaction in the income-tax return according to the applicable law. 5. What Changed in 2024? The Finance Act 2024 introduced an important structural change. Earlier understanding Many exporters operated under the perception: Export proceeds → tax deducted → final tax → matter finished Current framework The framework changed toward: Export proceeds → tax collected under applicable provisions → minimum-tax treatment → proper income-tax compliance FBR specifically warned in January 2026 that exporters' returns were being examined because the post-2024 legal framework needs to be correctly reflected in returns. (Federal Board of Revenue) Practical lesson for SMEs Do not copy the tax treatment from an old export return simply because it worked in previous years. Every exporter should review the current tax year separately. 6. Export Tax Rate in 2026 For FY 2026–27, the FBR's Budget 2026–27 salient features state that tax collection on export proceeds was rationalized, reducing the combined collection from 2% to 1.25%. (Federal Board of Revenue) The same FBR document also states that the reduced 0.25% rate for exporters of IT and IT-enabled services has been extended through Tax Year 2029. (Federal Board of Revenue) Important caution An exporter should not assume that 1.25% applies to every export-related receipt. The applicable treatment can depend upon: Nature of export Goods or services IT/IT-enabled services Export structure Applicable section Taxpayer classification Current Finance Act Relevant SRO/notification Therefore, the rate should always be checked against the applicable provision for the transaction. 7. Example: Understanding the 1.25% Collection Suppose an exporter has eligible export proceeds of: US$100,000 For illustration only, if the applicable collection rate is 1.25%: US$100,000 × 1.25% = US$1,250 The important point is that this is not automatically the same thing as saying the exporter's total income-tax liability is US$1,250. Because the current exporter regime involves minimum-tax treatment, the exporter's overall income-tax position must be determined under the applicable law and return requirements. 8. Sales Tax on Exports — Understanding Zero Rating One of the biggest areas of confusion among new exporters is the difference between: Zero-rated and Exempt These are not the same thing. Zero-rated supply A zero-rated transaction has a sales-tax rate of 0%, while the tax system can preserve input-tax recovery subject to the applicable conditions. The FBR's Tax Expenditure Report explains that zero rating means sales tax is applied at zero percent to specified items and identifies exports within the zero-rating framework. (FBR) Exempt supply An exempt supply is treated differently and generally does not provide the same input-tax recovery mechanism. Therefore: Zero-rated does not mean "nothing to document." In fact, exporters often need more documentation, because the zero-rating/refund chain must be supported. 9. Why Exporters Care About Zero Rating Imagine a manufacturer purchases: Raw materials Packaging Components Electricity-related taxable inputs Other taxable production inputs Sales tax may have been paid on eligible inputs. The manufacturer then exports the finished product. If the export is zero-rated, the exporter may have little or no output sales tax on the export transaction, while eligible input tax can potentially become refundable, subject to the applicable rules and verification. FBR states that registered manufacturer-cum-exporters and commercial exporters may claim sales-tax refunds in specified circumstances involving zero-rated supplies. (Federal Board of Revenue) 10. Sales Tax Refund — The Basic Concept A simplified example: Particular Amount Input Sales Tax paid Rs. 1,000,000 Output Sales Tax on export Rs. 0 Potential excess input tax Rs. 1,000,000 This does not automatically mean Rs. 1 million will be refunded. The refund is subject to: Eligibility Proper registration Valid input invoices Verification Export evidence Reconciliation Applicable refund procedures FBR's prescribed conditions FBR states that where input tax exceeds output tax because of exports or other zero-rated supplies, the excess input can be refunded subject to the applicable procedure and conditions. (Federal Board of Revenue) 11. Who May Need Sales Tax Registration? FBR's registration guidance includes persons making zero-rated supplies, including commercial exporters who intend to obtain sales-tax refunds against zero-rated supplies. (Federal Board of Revenue) The registration framework also covers categories such as: Importers Certain manufacturers Wholesalers/distributors Certain retailers Other persons required under applicable law Therefore, an SME should determine its registration obligations before starting regular export operations. 12. The Export Supply Chain A useful way for SMEs to understand export taxation is to divide the supply chain into stages. Stage 1 — Purchase The exporter purchases: Raw materials Finished goods Packaging Components Services Stage 2 — Production/Processing If the exporter is a manufacturer: Raw material → Production → Finished goods Stage 3 — Domestic movement Goods may move between: Factory Warehouse Processing unit Exporter Freight forwarder Port/airport Stage 4 — Export documentation The exporter prepares the required: Commercial invoice Packing list Goods Declaration Transport documents Other certificates where required Stage 5 — Customs clearance Customs verifies and processes the export declaration under the applicable procedures. Stage 6 — Shipment Goods leave Pakistan. Stage 7 — Foreign payment The buyer pays through the permitted banking/financial channel. Stage 8 — Tax reconciliation The exporter reconciles: Invoice → GD → shipment → bank receipt → accounting records → tax return This final reconciliation is extremely important. 13. Supply Chain Segregation For SMEs, one of the best compliance practices is supply-chain segregation. Maintain separate records for: Export sales and Domestic sales Do not mix everything into one spreadsheet. A proper accounting system should be able to distinguish: Category Record separately Domestic sales Yes Export sales Yes Export customer Yes Export invoice Yes Export proceeds Yes Input purchases Yes Export-related inputs Yes Domestic-use inputs Yes Refundable input tax Yes Export expenses Yes This makes tax-return preparation and audit/reconciliation substantially easier. 14. Export Documentation Checklist An exporter should establish a document file for every shipment. Commercial documents Purchase order Sales contract Proforma invoice Commercial invoice Packing list Certificate of origin where required Product-specific certificates where applicable Customs documents Goods Declaration PCT/HS classification evidence Customs-related documentation Export declaration records Examination/clearance records where applicable Shipping documents Depending on the mode: Bill of Lading Air Waybill Railway receipt Postal receipt Other applicable transport documents Banking documents Bank export realization record Bank credit advice Payment evidence Relevant foreign-exchange documentation Tax documents Sales-tax invoices Purchase invoices Input-tax records Sales-tax returns Income-tax records Withholding/collection evidence FBR's sales-tax refund guidance specifically identifies input invoices, export Goods Declaration, transport documents and bank credit advice among documentation relevant to refund claims. It also notes that where imports/exports are processed through WeBOC, the Goods Declaration may be cross-matched electronically rather than requiring physical submission in the stated circumstances. (Federal Board of Revenue) 15. The Golden Reconciliation Rule For every export shipment, an SME should be able to answer: Where did this sale start, where did it go, and where did the money arrive? Ideally: Sales Contract ↓ Commercial Invoice ↓ Packing List ↓ Goods Declaration ↓ Shipping Document ↓ Foreign Buyer Payment ↓ Bank Record ↓ Accounting Entry ↓ Income Tax Return ↓ Sales Tax Return/Refund Record If these records don't agree, the exporter may face questions during scrutiny. 16. Product Classification — Why HS/PCT Matters Every exporter needs to understand the product classification system. The product's HS/PCT classification can influence: Customs treatment Export restrictions Import-input classification Regulatory requirements Certificates Concessions Statistical reporting Applicable duties or regulatory measures FBR publishes the current Pakistan Customs Tariff for FY 2026–27, including the updated Fifth Schedule. (Federal Board of Revenue) SME advice Do not select a PCT code simply because: "Someone else exports the same product under this code." Verify the classification based on the actual product. 17. Are All Exports Completely Free From Customs Charges? No. A common misconception is: "Exports have zero tax, so there can never be any customs-related charge." That is incorrect. The applicable treatment depends on the product, scheme and current legal framework. FBR maintains a list of operative customs SROs for exports, including export-related schemes and exemptions. (Federal Board of Revenue) Therefore, an exporter should verify whether a particular product is subject to: Regulatory duty Export restriction Special SRO Concession Export scheme Documentation requirement 18. Export Facilitation Schemes Pakistan has various customs/export facilitation mechanisms. One important framework is the Export Facilitation Scheme 2021, listed by FBR among operative export-related SROs. (Federal Board of Revenue) Such schemes can be particularly relevant to manufacturers who: Import raw materials Manufacture goods in Pakistan Export finished products The advantage can be significant, but the exporter must satisfy the relevant conditions and maintain proper inventory/accounting records. 19. Exporter vs Manufacturer-Cum-Exporter These two businesses should not be treated identically. Commercial Exporter A commercial exporter may: Purchase finished goods → Export them Manufacturer-Cum-Exporter A manufacturer-cum-exporter may: Import/purchase raw materials → Manufacture → Pack → Export The second model creates a much more detailed documentation chain. For example: 100 kg raw material ↓ Production ↓ 80 kg finished goods ↓ Export The business needs to be able to explain the relationship between the input and finished product. This is where inventory records and production records become important. 20. Input Tax Tracking If an exporter wants to claim sales-tax refunds, simply having purchase invoices is not enough. The business should maintain a system showing: Supplier → Invoice → Input Tax → Inventory → Production → Export Product For manufacturing SMEs, a basic input register can contain: Date Supplier Invoice Material Qty Value Sales Tax Used For 05-08-26 Supplier A INV-1001 Leather 500 kg Rs. X Rs. X Export 08-08-26 Supplier B INV-2050 Packaging 2,000 Rs. X Rs. X Export This creates a defensible audit trail. 21. Domestic and Export Sales Should Not Be Mixed Suppose a factory produces sanitaryware. It sells: Rs. 5 million domestically and Rs. 8 million internationally. The accounting system should distinguish the two. Why? Because the tax treatment, documentation and reconciliation requirements can differ. A simple management report could show: Sales Type Sales Domestic Rs. 5m Export Rs. 8m Total Rs. 13m Then the accounting system can identify which inputs and expenses relate to each activity. 22. Common Export Tax Mistakes Mistake 1 — Treating exports as "tax-free" Export transactions may receive zero-rating or other concessions, but that does not eliminate compliance. Mistake 2 — Using the old final-tax concept The exporter regime was changed through Finance Act 2024. (FBR) Mistake 3 — Incorrect PCT code Incorrect classification can cause customs and compliance problems. Mistake 4 — Missing bank reconciliation The export invoice and bank realization should be properly reconciled. Mistake 5 — Claiming unsupported input tax Only eligible and properly documented input tax should be claimed. Mistake 6 — Mixing domestic and export purchases This makes refund and tax reconciliation difficult. Mistake 7 — Poor invoice descriptions The description on commercial documents should accurately describe the product. Mistake 8 — Keeping documents only in WhatsApp/email Important records should be maintained systematically. Mistake 9 — Using outdated tax rates Tax rates and rules can change through Finance Acts and notifications. Mistake 10 — Assuming another exporter has the same tax treatment Two exporters selling apparently similar products may have different tax circumstances. 23. Export Tax Compliance System for an SME A small exporter can create five basic folders. Folder 1 — Customer Contract Purchase order Buyer details Correspondence Folder 2 — Shipment Invoice Packing list GD Bill of Lading/AWB Certificates Folder 3 — Purchases Supplier invoices Input tax Payment evidence Inventory records Folder 4 — Banking Export proceeds Bank advice Foreign currency records Payment reconciliation Folder 5 — Tax Sales tax returns Income tax returns Refund claims Tax deduction/collection certificates FBR correspondence This simple system can dramatically improve compliance discipline. 24. Monthly Export Reconciliation At the end of every month, the exporter should prepare a reconciliation. Particular Amount Export invoices Rs. ______ Goods Declarations Rs. ______ Shipment value Rs. ______ Bank realization Rs. ______ Accounting sales Rs. ______ Tax records Rs. ______ Difference Rs. ______ If there is a difference, investigate it before filing the return. 25. What if the Bank Amount Is Different From the Invoice? This can happen because of: Bank charges Commission Freight arrangements Insurance Discounts Short payments Exchange-rate differences Buyer deductions Contractual adjustments The important thing is not to hide the difference. Instead: Identify the reason. Obtain supporting documentation. Record the accounting adjustment. Reconcile the bank receipt. Keep the evidence with the export file. 26. Export Refunds — Documentation Discipline FBR's refund guidance identifies documentation such as: Input-tax invoices Import Goods Declarations where applicable Export Goods Declaration Bill of Lading/Airway Bill Bank credit advice Input-tax statements as relevant documentation for refund processing. (Federal Board of Revenue) This demonstrates an important principle: A refund claim is only as strong as the documentation supporting it. 27. What Small and Medium Enterprises Can Gain From Exporting Exporting isn't only about earning foreign currency. A properly documented exporter can potentially benefit from: 1. Access to international markets The business is no longer dependent entirely on local customers. 2. Foreign exchange earnings Exports generate foreign-currency receipts. 3. Production expansion International demand can justify increased capacity. 4. Better quality standards International buyers may require stronger quality controls. 5. Tax and customs facilitation Eligible exporters may access zero-rating, refunds and other export-related schemes subject to law. 6. Business credibility A documented export history can strengthen relationships with banks, buyers and business institutions. 28. Example — A Small Gujranwala Manufacturer Consider an SME manufacturing sports goods. Step 1 The manufacturer purchases raw materials. Step 2 Input invoices and sales tax are recorded. Step 3 Products are manufactured. Step 4 A foreign buyer places an order. Step 5 The exporter prepares commercial documentation. Step 6 The export declaration is filed. Step 7 The shipment leaves Pakistan. Step 8 The foreign buyer pays through the appropriate banking channel. Step 9 The exporter reconciles: Invoice + GD + shipping + bank receipt Step 10 The exporter records the transaction correctly in tax returns. Step 11 Where eligible, the exporter follows the applicable sales-tax refund process. This is the basic export compliance cycle. 29. Export Tax Compliance Checklist Before exporting: NTN/appropriate tax registration completed Sales-tax registration assessed Business registration completed Bank/export arrangements established Product PCT/HS classification checked Export restrictions checked Buyer verified Contract prepared Invoice format prepared Payment terms agreed For every shipment: Purchase order Commercial invoice Packing list Goods Declaration Shipping document Certificate of origin if required Product certificates if required Customs documentation Bank/payment evidence For tax compliance: Export sales recorded separately Input tax properly recorded Export proceeds reconciled Tax collected/deducted reconciled Sales tax return reviewed Income tax return reviewed Refund claim supported Records archived 30. The Exporter's "Four-Way Match" For a strong compliance system, compare four records: 1. Commercial Record Invoice 2. Customs Record Goods Declaration 3. Logistics Record Bill of Lading / AWB 4. Financial Record Bank Receipt If these four records tell the same story, your export file is much stronger. 31. What FBR Looks For in a Compliance Review An exporter should be prepared to demonstrate: What was exported? Who was the buyer? What was the value? What was the product classification? When was it exported? Did the goods actually leave Pakistan? Where is the customs declaration? Where is the shipping evidence? Where did the payment arrive? How was the transaction recorded? What input tax was claimed? How was the refund calculated? Was the income correctly declared? FBR's January 2026 clarification specifically confirms that desk review of exporters' returns is part of its statutory tax-administration responsibilities. (Federal Board of Revenue) 32. Exporter Compliance Dashboard An SME can maintain a simple dashboard: Area Status NTN ✅ Sales Tax Registration ✅/Review Bank Account ✅ Exporter Registration/Arrangements ✅ PCT Classification Review Customer Contract ✅ Commercial Invoice ✅ Packing List ✅ GD ✅ Shipping Document ✅ Bank Realization Pending Sales Tax Reconciliation Pending Income Tax Reconciliation Pending Refund Documentation Pending This is especially useful for businesses making multiple shipments every month. 33. Key Difference: Zero Rating vs Refund These concepts should not be confused. Zero rating Concerns the tax rate applied to the qualifying supply. Refund Concerns recovery of eligible input tax under the applicable rules. Therefore: Zero-rated does not automatically mean an immediate cash refund. The exporter must satisfy the refund requirements. FBR provides a specific refund framework and states that registered manufacturer-cum-exporters and commercial exporters can claim refunds in specified zero-rated circumstances. (Federal Board of Revenue) 34. Exporters Should Monitor FBR Updates Tax laws are not static. For example, FBR's current resources already reflect: Finance Act 2026 changes Tax Year 2027 withholding-tax rate card FY 2026–27 customs tariff Updated income-tax legislation Current export-related SROs FBR's current withholding-tax page identifies the Tax Year 2027 rate card updated through 30 June 2026 under Finance Act 2026. (Federal Board of Revenue) Therefore, exporters should avoid relying indefinitely on: Old YouTube videos Old consultant templates Old Excel sheets Old tax rates Old FBR screenshots Previous-year return settings 35. Practical Advice for New Pakistani Exporters If you are an SME preparing to export for the first time, don't start with: "How can I export?" Start with: Step 1 What exactly am I exporting? Step 2 What is the correct PCT/HS classification? Step 3 Is the product subject to any export restriction or special requirement? Step 4 What registrations do I need? Step 5 What is the applicable sales-tax treatment? Step 6 What is the current income-tax treatment? Step 7 What documents will my bank require? Step 8 What documents will Customs require? Step 9 How will I track my input tax? Step 10 How will I reconcile the export proceeds? This approach prevents many problems before they occur. 36. Final Export Tax Compliance Model The complete system can be remembered as: PRODUCT ↓ PCT/HS CLASSIFICATION ↓ BUYER & CONTRACT ↓ INVOICE ↓ INPUT & INVENTORY RECORDS ↓ CUSTOMS / GD ↓ SHIPMENT ↓ BANK REALIZATION ↓ ACCOUNTING ↓ SALES TAX RECONCILIATION ↓ INCOME TAX COMPLIANCE ↓ REFUND / ADJUSTMENT WHERE ELIGIBLE ↓ DOCUMENT RETENTION That is the foundation of a properly managed export business. 37. Conclusion Export taxation in Pakistan should not be viewed simply as a tax percentage deducted from a foreign payment. It is a complete compliance ecosystem involving: FBR + Customs + Banking + Sales Tax + Income Tax + Documentation + Accounting + Export Regulations. For SMEs, the most important principle is documentation discipline. An exporter should be able to connect: Product → Invoice → GD → Shipment → Bank Receipt → Accounting → Tax Return without unexplained differences. The Finance Act 2024's change from the previous final-tax treatment for exporters to a minimum-tax framework makes this even more important. FBR's 2026 guidance confirms that exporters' returns need to reflect the changed legal framework correctly. (Federal Board of Revenue) At the same time, exporters should understand that zero-rated exports are not the same as tax-free business activity. Zero-rating can allow eligible input-tax recovery/refund mechanisms, but those benefits depend on proper registration, documentation, reconciliation and compliance. (Federal Board of Revenue) For a small Pakistani manufacturer or trader looking to enter international markets, the safest strategy is therefore: Export professionally → document everything → reconcile everything → file correctly → monitor FBR updates. Quick Reference — Export Taxation in Pakistan Topic Key Point Income Tax Exporter regime changed from final tax to minimum tax through Finance Act 2024 Export proceeds Current collection framework should be checked under the applicable year FY 2026–27 FBR states export-proceeds collection was rationalized to 1.25% IT/ITeS exports FBR states 0.25% concession extended through TY2029 Sales Tax Qualifying exports fall within the zero-rating framework Refund Eligible input tax may be refundable subject to conditions Customs Product classification and current tariff must be checked Documentation Invoice, GD, shipping and bank records should reconcile SMEs Separate domestic and export accounting Compliance Current Finance Act/SROs should always be verified FBR currently provides the authoritative sources for the Income Tax Ordinance, Customs Tariff, withholding-tax rate cards, sales-tax refund procedures and export-related SROs. (Federal Board of Revenue) Suggested training-session GCCI R&D Training Center — Understanding Taxes on Exports in Pakistan: FBR Rules, Zero-Rating, Refunds & Export Compliance This would work particularly well as a GCCI R&D Training Center SME awareness article, because it teaches exporters not just what tax is charged, but how to build a compliant export transaction from purchase to bank realization.
-
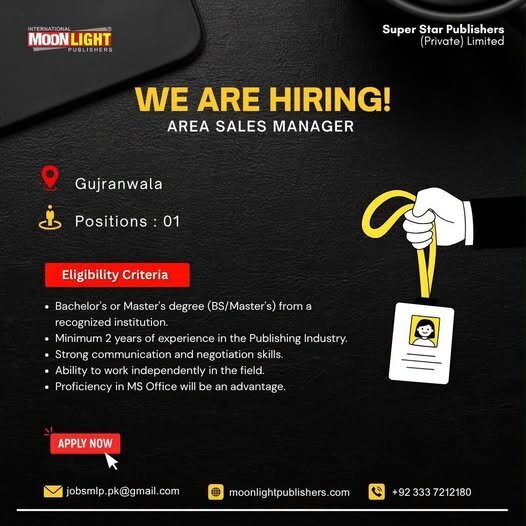 click here to get details for apply.
-
We’re Hiring – HR & Office Manager Associate 📢 Full-time opportunity in Gujranwala for candidates with 1–3 years of HR or office management experience. Apply now via email and website links are not allowed or 03278614399. HR & Office Manager Associate – Job Opportunity in Gujranwala Are you looking for an HR and Office Management job in Gujranwala? An exciting opportunity is available for a HR & Office Manager Associate at Opposite Commissioner House, DC Road, Gujranwala. We’re looking for a detail-oriented and people-focused professional who can manage HR operations and help maintain a smooth, organized, and productive workplace. 📌 Position HR & Office Manager Associate 💼 What You’ll Do Manage employee records, attendance, leaves, and HR documentation Support recruitment, onboarding, and employee coordination Handle employee queries and ensure policy compliance Oversee daily office operations and administration Coordinate office supplies, vendors, and maintenance Ensure a professional and efficient work environment 🎯 What We’re Looking For 1–3 years of experience in HR or office management Strong communication and organizational skills Proficiency in MS Office / Google Workspace Ability to handle sensitive information with confidentiality Proactive, responsible, and able to work independently Good command of English and Urdu 📍 Job Details Location: Opposite Commissioner House, DC Road, Gujranwala Employment Type: Full Time Timing: 2:00 PM – 11:00 PM Position: HR & Office Manager Associate 📩 How to Apply Interested candidates can apply by contacting: Email: email and website links are not allowed Phone: 03278614399 If you have relevant HR or office management experience and are looking for a full-time career opportunity in Gujranwala, this position may be a good fit for you. #JobsInGujranwala #GujranwalaJobs #HRJobs #HRJobsPakistan #OfficeManagerJobs #HRManager #HRAssociate #OfficeManagement #AdministrationJobs #FullTimeJobs #JobsPakistan #CareerOpportunity #Hiring #WeAreHiring #JobVacancy #LatestJobs #PrivateJobs #Gujranwala #HumanResources #CareerPakistan #Employment #JobSearch #HiringNow #Jobs2026 #FundayForum
-
us smart living US Smart Living – Smart Ideas for Better Everyday Life
Waqas Dar posted a gallery image in Funday Open Gallery
 US Smart Living brings you practical tips, smart ideas, technology, home, money, travel, shopping, lifestyle guides and useful information for everyday life in America. Smart ideas, helpful guides and useful information for modern American living — covering technology, home, money, travel, shopping and lifestyle. #FundayForum #SmartLiving #USLifestyle #AmericanLifestyle #LifeTips #DailyTips #HelpfulTips #TrendingNow #LifestyleTips #SmartTips #UsefulInformation #HowTo #TipsAndTricks #OnlineCommunity #CommunityForum #LatestUpdates #TrendingTopics #EverydayLife #DigitalLifestyle #USAudience
© Fundayforum.com
-
jobs in gujranwala dar-E-Arqam School jobs In Gujranwala
Waqas Dar posted a gallery image in Funday Open Gallery
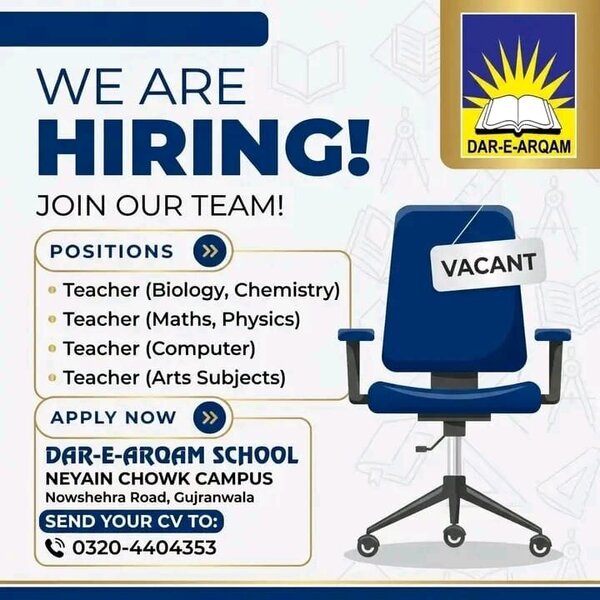 Dar-e-Arqam School These are the vacancies available. Apply Now for : Teacher (biology/Chemistry) Teacher ( Math/Physics ) Teacher ( Computer ) Teacher ( Arts Subjects ) Send your CV to: 0320-4404353
© Fundayforum.com
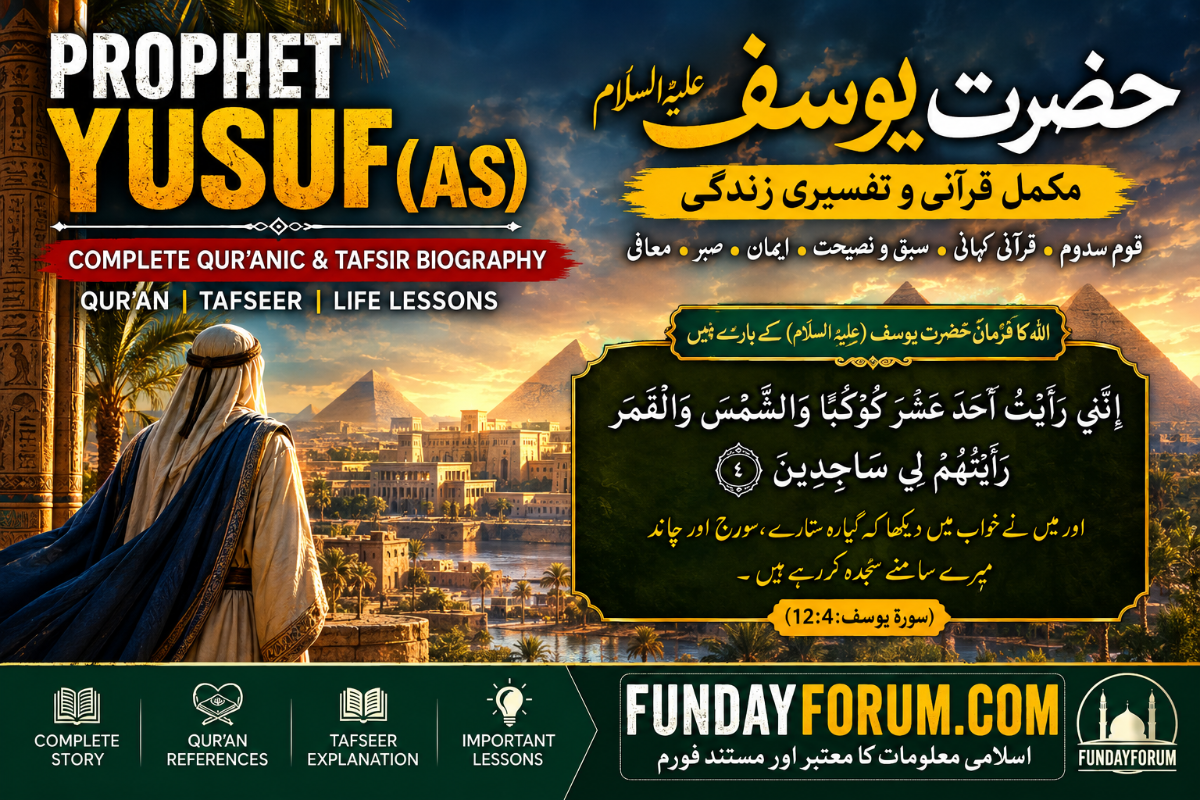
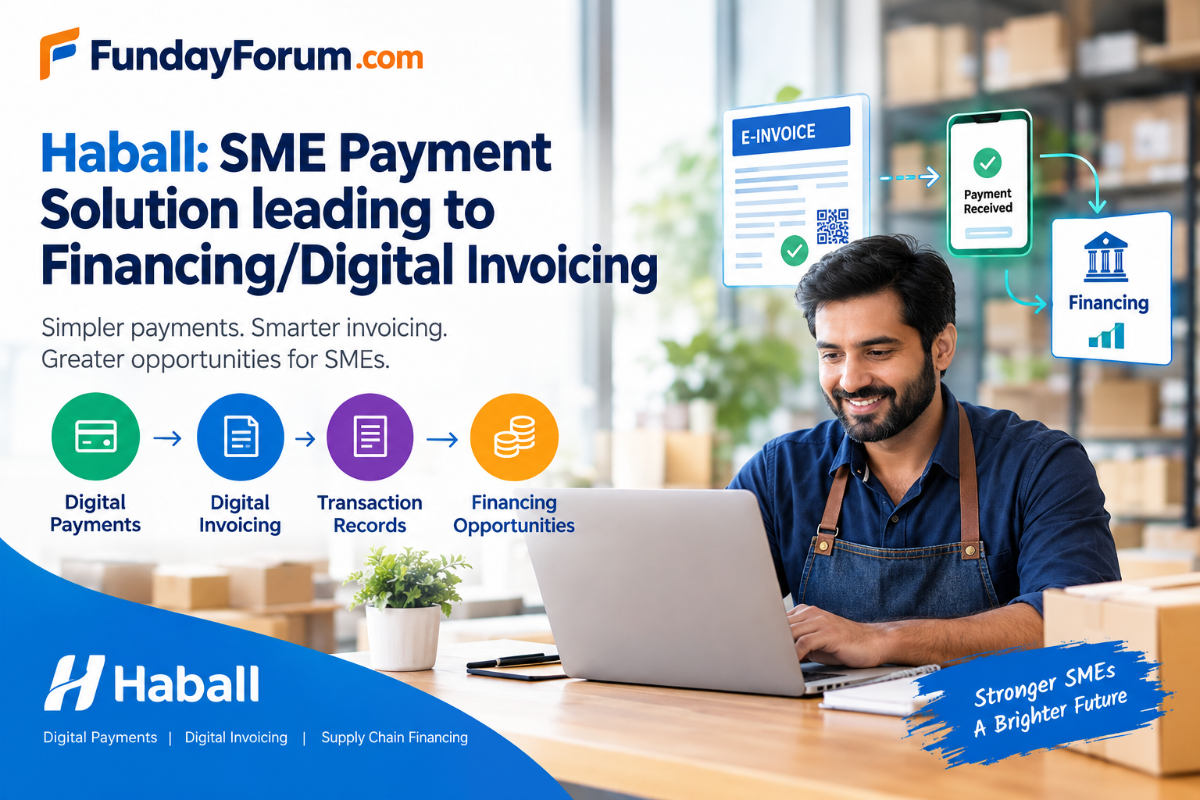
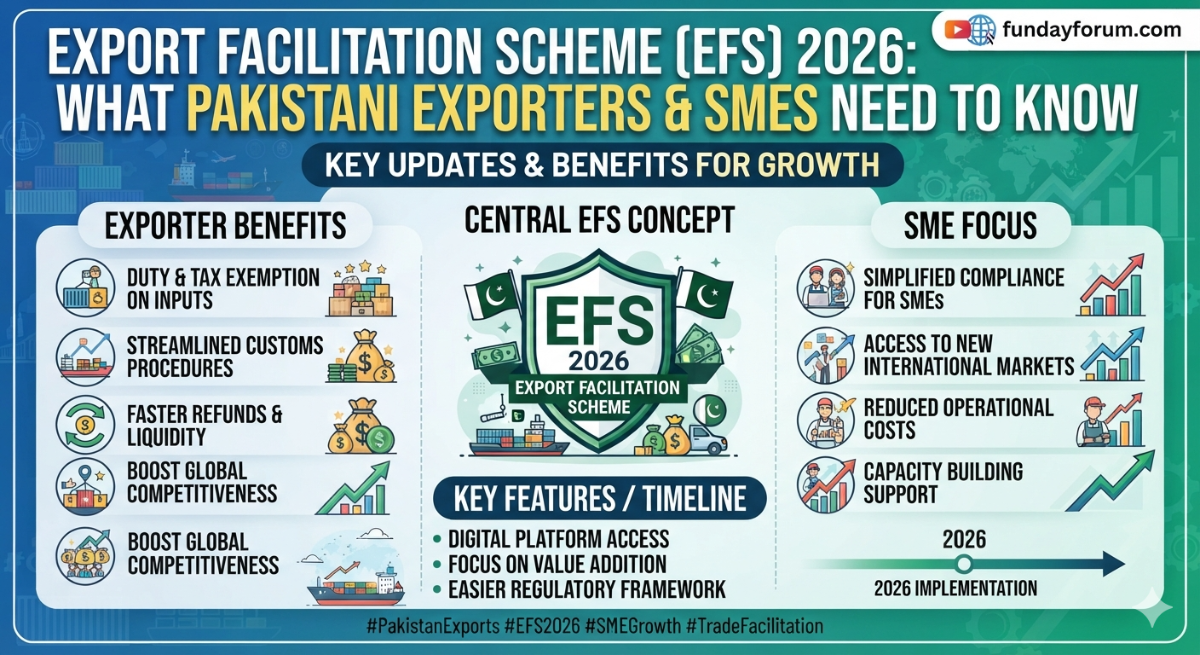
-
Recently Browsing 0 members
- No registered users viewing this page.