- 📢 Welcome to FundayForum – Explore Trending Topics
- 🌟 Discover What’s Trending Today
- Prince Harry delights Meghan with good news: 'Doors will open'
- Kanye West treats his kids to a very expensive surprise
- Dua Lipa thanks Shakira after ‘Antología' duet: ‘So grateful'
- Andrew Mountbatten-Windsor ‘working on comeback' with help of surprise ally
- John Nellis breaks exciting baby news during 'Strictly' appearance
- Lauren Silverman accepts responsibility for her past mistakes
- Asian Games close in Japan after records, rancour and rain
- Andrew Garfield teases 'Spider-man' return: 'Never say never'
- Anne Hathaway hilariously vanishes in plume of smoke after ‘Verity' debut
- King Charles team takes action to protect Buckingham Palace from intruders
🗳️ Poll Vote
2 PSL 2026 Champion Prediction Vote
-
1. Which team will win PSL 2026 trophy?
-
🟡 Islamabad United (IU)
-
🟢 Lahore Qalandars (LQ)
-
🔵 Karachi Kings (KK)
-
🟣 Peshawar Zalmi (PZ)
-
🔴 Multan Sultans (MS)
-
🟠 Quetta Gladiators (QG)
-
🔷 Hyderabad Kingsmen (HK)
-
⚫ Rawalpindi Franchise (RP)
-
- Please sign in or register to vote in this poll.
- View topic
⭐ Our Picks
Our picks
-

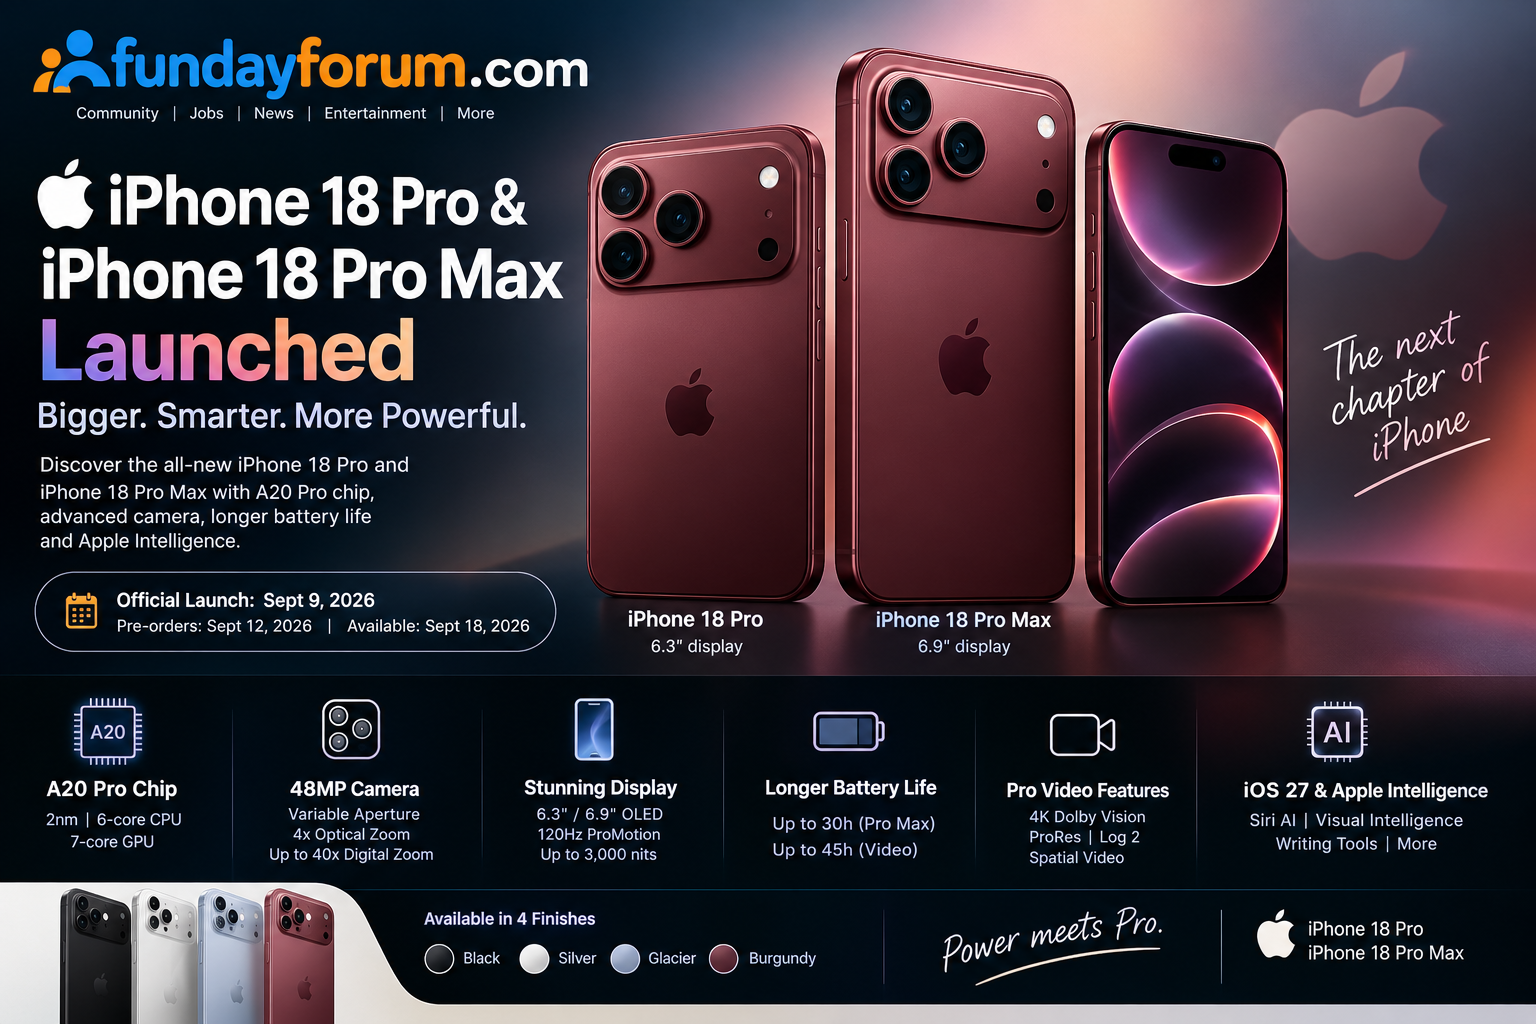
iPhone 18 Pro & iPhone 18 Pro Max Launched: Full Specifications, Features, Camera, Price & Battery
Waqas Dar posted an article in Technology,
Apple iPhone 18 Pro and iPhone 18 Pro Max officially launched in 2026 with A20 Pro performance, a 48MP variable-aperture camera and upgraded battery life.-
1
Reputation Points
- 0 replies
Picked By
Waqas Dar, -
-
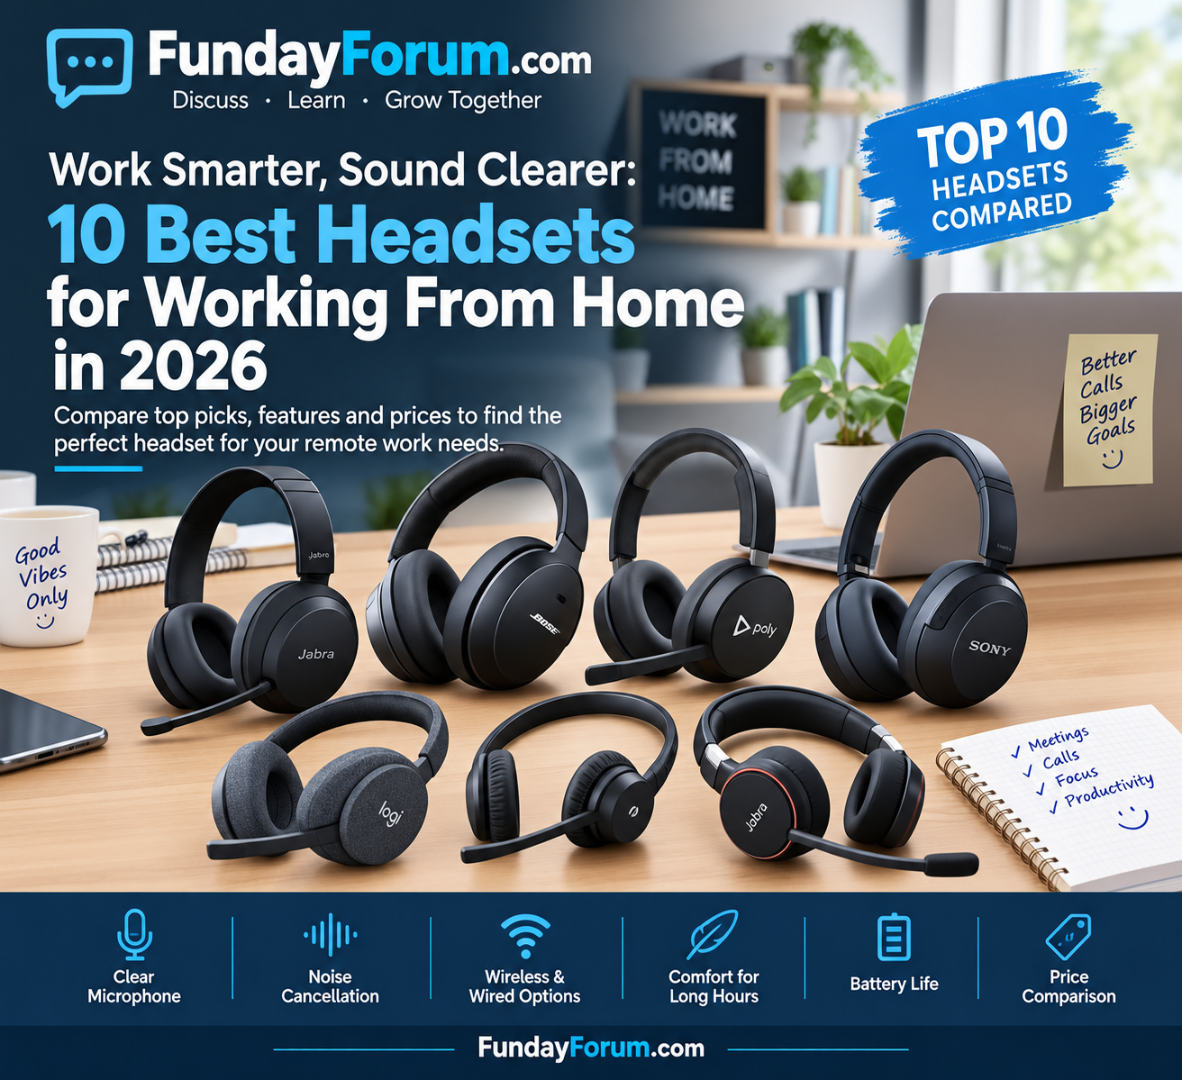
10 Best Headsets for Working From Home in 2026 – Price & Comparison Guide
Waqas Dar posted an article in Technology,
Discover the 10 best headsets for remote work in 2026. Compare popular Jabra, Logitech, Poly, Sony, and Bose models to find the right headset for online meetings, customer support, freelancing, and home office productivity.
Work Smarter, Sound Clearer: 10 Best Headsets for Remote Work in 2026
Category: Technology / Home Office / Buying Guides
Year: 2026
Reading Time: 10–12 minutes
Introduction
Working from home has become a regular part of modern professional life. Whether you are attending Zoom meetings, managing customer support calls, working as a freelancer, or handling international clients, your headset plays an important role in daily productivity.
A good headset helps you communicate clearly, reduce distractions, and remain comfortable during long working hours. However, choosing the right model can be difficult because the market offers everything from affordable wired USB headsets to premium wireless devices with advanced noise cancellation.
In this guide, we explore 10 headsets worth considering for remote work in 2026, comparing their microphones, connectivity, comfort, battery life, and estimated prices.
Our focus: Practical choices for professionals who need reliable audio for meetings, customer service, online teaching, freelancing, and everyday office tasks.
Price note: Prices below are indicative US-dollar estimates, not guaranteed live retailer offers. Actual prices vary by retailer, configuration, regional availability, and promotions. Verify the latest price before purchasing.
-
1
Reputation Points
- 0 replies
Picked By
Waqas Dar, -
-
10 Best Gaming Headsets in 2026 – Footstep Audio, Comfort & Mic Quality
Waqas Dar posted an article in Technology,
Compare 10 gaming headsets for 2026, focusing on the features gamers actually use: accurate positional audio, clear microphones, long-session comfort, low-latency wireless and battery life.
-
0
Reputation Points
- 0 replies
Picked By
Waqas Dar, -
-
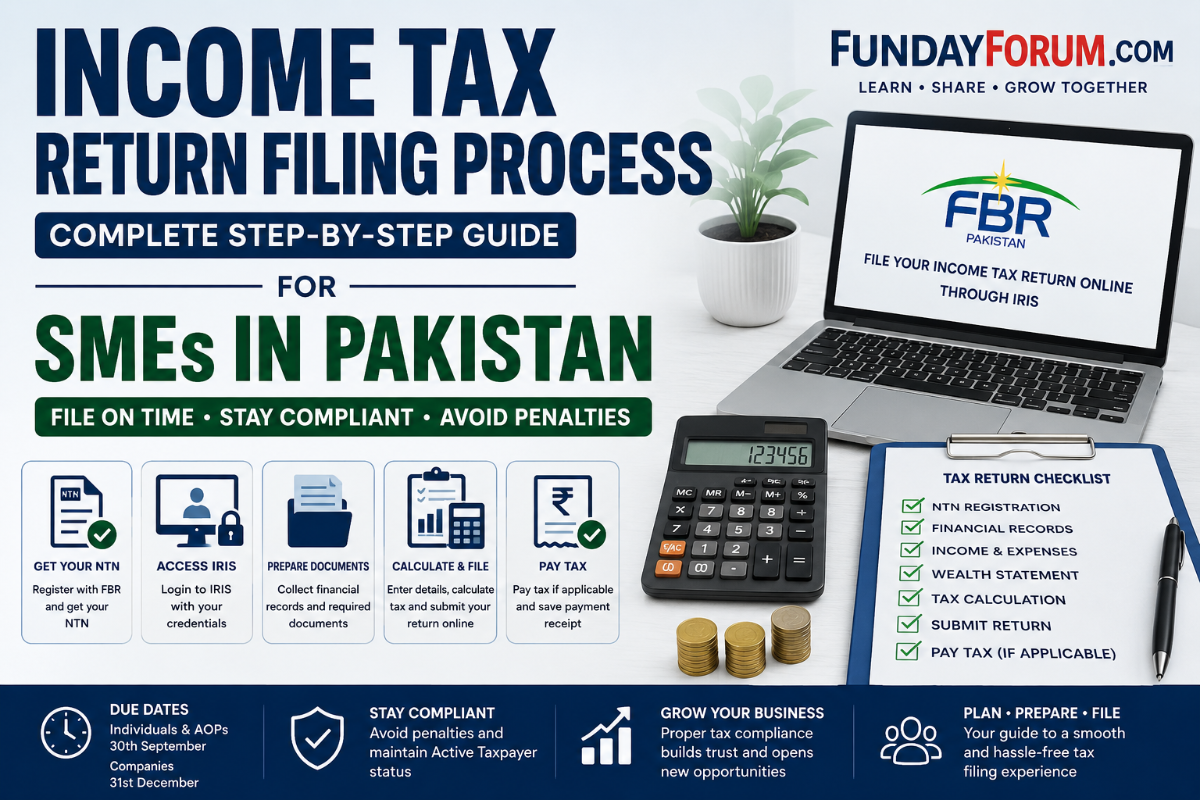
Income Tax Return Filing Process in Pakistan – Complete Step-by-Step Guide for SMEs
ADMIN posted a topic in 💼 Business, Trade, Export & Tax Hub,
Complete step-by-step guidance for SMEs in Pakistan on NTN registration, IRIS return filing, financial records, tax calculation, Wealth Statement, payment and timely income tax compliance.
Income Tax Return Filing Process in Pakistan – Complete Step-by-Step Guide for SMEs
Introduction
Filing an Income Tax Return is an important part of running a compliant business in Pakistan. Small and Medium Enterprises (SMEs), traders, manufacturers, service providers, freelancers and other businesses should maintain proper financial records and fulfill their applicable tax filing obligations.
The Federal Board of Revenue (FBR) uses the IRIS online system for income tax registration and online return filing. FBR states that e-enrollment provides the taxpayer with an NTN or registration number and access credentials for IRIS. (Federal Board of Revenue)
This guide explains the income tax return filing process for SMEs in Pakistan step by step, including registration, required documents, preparation of financial information, filing through IRIS, tax payment, record keeping and common mistakes.
1. Understand Your Business Tax Status
Before filing your return, first identify how your business is legally structured.
An SME may operate as:
Sole Proprietorship / Individual Business
Partnership / Association of Persons (AOP)
Private Limited Company
Single Member Company
Other company structures
The filing requirements and applicable return forms can differ according to the taxpayer's legal status and type of income.
-
0
Reputation Points
- 0 replies
Picked By
Waqas Dar, -
📸 Random Images
Random Images









📚 Latest Albums
Most Viewed Albums
-
WhatsApp Status 💕
- By jannat malik,
- 3
- 13
- 80
-
Wallpapers
- By Shiza sheikh,
- 0
- 8
- 88
-

Urdu Poetry Wallpaper Design Fundayforum
- By Waqas Dar,
- 0
- 8
- 7
-

Funny Quotes and Lines
- By Waqas Dar,
- 0
- 2
- 9
📥 Download Files

🏆 Top Downloads
Top Downloads
Week


Month

Year
All Time


📡 Active Stream
Active Stream
📰 Latest Posts
latest Posts
-

ADMIN 348

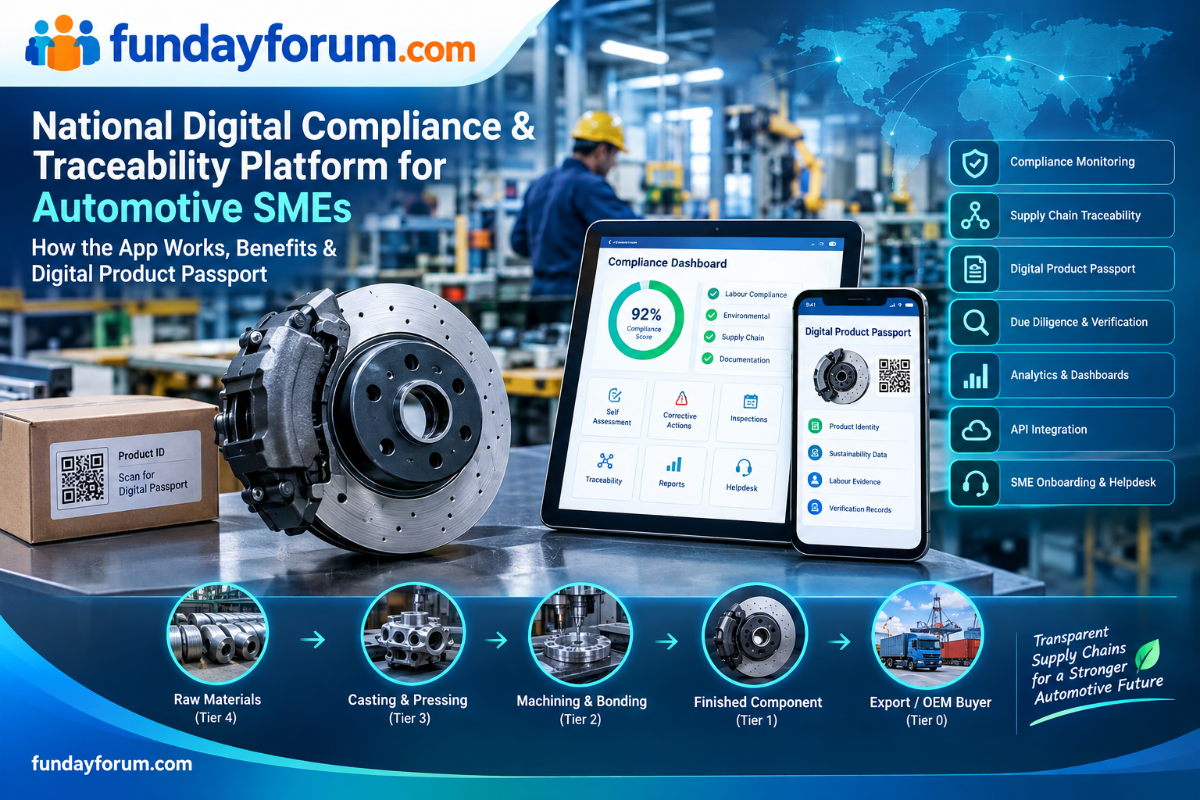
National Digital Compliance & Traceability Platform for Automotive SMEs — connecting compliance, supply-chain traceability, QR-based product identification and Digital Product Passport readiness. National Digital Compliance & Traceability Platform for Automotive SMEs – How the App Works, Benefits, Supply Chain & Digital Product Passport
National Digital Compliance & Traceability Platform is a proposed secure and interoperable digital platform designed to bring labour compliance, SME formalization, supply-chain traceability and Digital Product Passport (DPP) readiness into one connected system.
The platform presentation uses the automotive sector and a front disc-brake assembly as a practical case study to demonstrate how an SME, its suppliers, inspectors, regulators and international buyers can work through a connected digital ecosystem.
🚗 1. Why Does the Automotive Sector Need a Digital Compliance & Traceability Platform?
Automotive supply chains can involve many businesses, from raw-material suppliers and casting units to machining companies, component manufacturers, assemblers and international OEM buyers.
The presentation identifies a major challenge: compliance evidence is often fragmented across regulators, OEMs, multi-tier suppliers and paper-based workflows. Tier 2–4 vendors can remain difficult to identify and verify, even though their activities may directly affect the final exported product.
Key challenges
- Fragmented compliance documentation
- Paper-based and manual workflows
- Limited digital capability among SMEs
- Limited visibility of Tier 2–4 suppliers
- No unified multi-tier BOM traceability
- Manual inspections and corrective actions
- Limited risk scoring and centralized dashboards
- Growing international demand for verifiable supply-chain evidence
- Need for product-level Digital Product Passport readiness
The proposed platform is intended to turn this fragmented information into structured, trusted and auditable digital data.
💻 2. What Is the National Compliance & Traceability Platform?
The proposed platform is a modular national web application combining several functions in one ecosystem.
- Compliance Monitoring – enterprise profiles, self-assessments, compliance rules and gap identification.
- Due Diligence – document submission, verification, inspections, grievances and corrective actions.
- Digital Product Passport – product-level compliance and sustainability information.
- Supply Chain Traceability – raw material to finished product and export, including Tier 1–4 visibility.
- Dashboards & Analytics – KPIs, risk scoring, heat maps and reports.
- API Interoperability – connection with relevant government, sectoral and social-security systems.
- Web Application – English/Urdu and field-user oriented, with offline-capable workflows.
- Helpdesk & SME Onboarding – guided registration, tickets, guidance and notifications.
The presentation describes the system as secure, scalable, government-owned and suitable for national reporting and international due-diligence requirements.
⚙️ 3. How Will the App Work for an SME?
Step 1 – SME Registration
The SME creates an enterprise profile containing information such as its registration, sector, HS code, facility and role in the supply chain.
For example, the presentation uses Bravo Brake Systems as a representative automotive enterprise registering for brake assemblies under HS 8708.30.
Step 2 – Guided Self-Assessment
The SME completes guided compliance checklists covering relevant labour and environmental parameters.
This approach is designed to make compliance easier for smaller businesses that may not have dedicated compliance departments.
Step 3 – Compliance Scoring
A configurable rules engine evaluates the information and identifies compliance gaps.
Instead of simply storing documents, the system can show the SME where improvement is required.
Step 4 – Corrective Action
Identified gaps can become corrective actions with deadlines, evidence requirements and verification workflows.
Step 5 – Verification & Inspection
Documents can be submitted and verified, inspections can be scheduled and findings can be digitally recorded.
Worker grievances and non-compliance issues can also be logged and followed through the platform.
Step 6 – Supply Chain Mapping
The SME's product can be connected to relevant upstream suppliers and manufacturing stages, creating a structured supply-chain record.
Step 7 – QR / Barcode & Product Passport
The finished product or batch can be associated with a QR code, barcode or batch ID. Authorized users can then retrieve the permitted product and compliance information.
Step 8 – Continuous Monitoring
The SME dashboard provides its compliance status, action plan, certificates and helpdesk cases so that compliance becomes an ongoing process rather than a one-time registration activity.
The platform's core compliance module specifically includes enterprise profiles, guided self-assessment, a configurable rules engine and corrective-action workflows.
🔗 4. Automotive Example – Front Disc-Brake Assembly
The presentation demonstrates the traceability model through a front disc-brake assembly.
Tier Stage Example Information Tier 4 Steel & friction compound Origin, lot and supplier information Tier 3 Casting & pressing Caliper and pad batch evidence Tier 2 Machining & bonding Sub-assembly and testing records Tier 1 Finished assembly QR / DPP linkage Tier 0 Export / OEM buyer Verified product passport This multi-tier structure allows the platform to follow a component from its raw-material sources through manufacturing and ultimately to the international buyer.
📱 5. How Does QR-Code Traceability Work?
- A product or batch receives a unique digital identity.
- The identity is linked to the platform's product record.
- Supplier and production information is connected to the relevant BOM.
- Compliance and sustainability evidence is attached to the appropriate record.
- An authorized user scans the QR/barcode.
- The platform retrieves the permitted product/passport information.
- Buyers, auditors or inspectors can verify the available evidence according to their access rights.
The proposed field-inspector workflow is:
Scan QR → Open Facility Profile → Conduct Checklist → Upload Evidence → Sync Offline/Online → Trigger Corrective Action
📋 6. What Can the Digital Product Passport Contain?
The automotive component passport described in the presentation can contain several categories of information.
Product Identity
- QR/barcode
- Batch ID
- Exporter linkage
Sustainability Information
- Recycled steel content
- Casting and machining energy information
- Relevant mass-balance factors
Labour Evidence
- Factory certification
- Workforce compliance
- Due-diligence information
Verification
Controlled retrieval of information can be provided for authorized OEM buyers and auditors.
The intended result is auditable product information that can be verified rather than relying solely on unsupported declarations.
🏭 7. How Will This App Help Automotive SMEs?
1. Easier Compliance Management
SMEs can use guided checklists, compliance scoring and corrective-action plans instead of managing compliance entirely through scattered paperwork.
2. Better Supply-Chain Visibility
Smaller Tier 2–4 suppliers can become visible within the automotive supply chain.
3. Export Readiness
The platform can organize the evidence and product information needed for buyer due-diligence processes.
4. Digital Product Passport Readiness
SMEs can begin organizing product identity, sustainability, labour and verification information in a structured digital format.
5. Corrective-Action Guidance
Compliance gaps can be converted into actions with deadlines and evidence requirements.
6. English & Urdu Access
The proposed application is intended to support English and Urdu, helping make onboarding more accessible for local SMEs.
7. Offline-Capable Field Work
The platform scope includes offline-capable field-user workflows for situations where continuous connectivity may not be available.
8. Helpdesk & Guidance
SMEs can receive guidance, notifications and helpdesk support through the platform.
9. Centralized Records
Compliance status, certificates, corrective actions and traceability information can be managed from one digital environment.
The presentation specifically identifies simple SME onboarding, English/Urdu access, offline capability, certificates and guidance as SME requirements.
📊 8. What Will the SME Dashboard Show?
- Compliance score/status
- Open compliance gaps
- Corrective-action plan
- Deadlines
- Required evidence
- Certificates
- Verification records
- Supply-chain information
- Product passport information
- Helpdesk cases
- Notifications
Other stakeholder groups receive different dashboards according to their responsibilities. NCC/ILO can view national indicators, provincial departments can view inspections and hotspots, SMEs can view their own compliance status, while associations and partners can access aggregated benchmarks.
🔍 9. Due-Diligence Workflow
The due-diligence module converts documents, inspections, grievances and corrective actions into an auditable compliance trail.
- Document submission
- Document validation
- Document verification
- Inspection scheduling
- Inspection reporting
- Grievance recording
- Non-compliance tracking
- Corrective-action assignment
- Evidence upload
- Verified sign-off
- Risk scoring
The presentation illustrates this process with a sample batch audit trail in which each activity is time-stamped and the resulting compliance/risk status can be followed.
🏛️ 10. How Can Existing Government Systems Connect?
The proposed architecture is API-first. The objective is to connect existing systems rather than replace every existing database.
- SECP: business registration
- FBR: tax / NTN verification
- SMEDA: SME registry and profiling
- EDB / PAMA: automotive-sector information
- EOBI / PESSI / SESSI: social-security information
- Provincial systems: inspection and enforcement information
- PSQCA / PNAC: testing and certification infrastructure
The architecture uses a governed API gateway, OpenAPI 3.0, role-based access control and audit logs.
🔐 11. Security & Data Protection
Security is presented as part of the platform architecture from the beginning.
- Identity & Access: OAuth/OpenID, MFA and granular role-based access.
- Data Protection: TLS 1.3 and AES-256 with purpose limitation.
- Auditability: immutable logs, export controls and traceable changes.
- Testing: OWASP practices, vulnerability scanning and penetration testing.
The presentation also specifies role-based access, audit trails, data protection, purpose limitation and governed interoperability as core data-governance principles.
🌍 12. International Compliance & Export Readiness
The presentation identifies several regulatory and international-market drivers relevant to export-oriented businesses:
- GSP+: verifiable labour standards evidence
- EU CSDDD: supply-chain due-diligence
- ESPR / ELV: product and vehicle circularity passport readiness
- ILO Frameworks: decent work, just transition and SDG alignment
The deck also discusses the EU ESPR Working Plan, automotive-relevant steel and tyres, the End-of-Life Vehicles Regulation and future battery/DPP requirements. Specific legal requirements and dates should always be checked against the latest official regulatory documents before an SME relies on them for an actual export transaction.
🧑💼 13. Example: How a Small Automotive Supplier Could Use the Platform
Imagine a small machining company supplying components to a Tier 1 automotive manufacturer.
- The company registers on the platform.
- It creates its enterprise and facility profile.
- It identifies its sector, product and relevant HS information.
- It completes the guided compliance assessment.
- The platform identifies compliance gaps.
- The SME uploads the required evidence.
- Corrective actions are completed and verified.
- The company's product is connected to the relevant supply-chain/BOM record.
- Batch or product information is linked with its digital identity.
- Authorized buyers or auditors can verify permitted information.
- The SME continues updating its records as compliance and production information changes.
This creates a continuous digital relationship between SME → compliance → supplier → product → traceability → buyer.
📈 14. Main Benefits for Automotive SMEs
Area Platform Support Compliance Self-assessment, scoring, evidence and corrective actions Traceability Tier 1–4 supply-chain and BOM visibility Export Readiness Structured compliance and product evidence DPP Readiness QR/barcode-linked product information Inspections Digital scheduling, findings and follow-up Worker Processes Grievance and non-compliance tracking SME Support English/Urdu onboarding and helpdesk Reporting Dashboards, KPIs, risk scoring and reports Interoperability API connections with existing systems
🔄 15. Complete Platform Workflow
SME Registration → Enterprise Profile → Self-Assessment → Compliance Score → Gap Identification → Corrective Action → Evidence Upload → Verification / Inspection → Supply-Chain Mapping → QR / Product ID → Digital Product Passport → Buyer / Auditor Verification → Continuous Monitoring
This combines the major modules described in the presentation into one practical SME journey.
👥 16. Key Stakeholders
- NCC: national strategic oversight and data governance
- ILO: technical guidance and quality assurance
- SMEDA: SME onboarding, profiling and registry integration
- Provincial Departments: inspections and enforcement workflows
- SECP / FBR / EOBI / PESSI / SESSI: registration, tax and social-security interoperability
- EDB / PAMA / PSQCA: automotive-sector policy, membership and testing/certification ecosystem
- SMEs & Suppliers: registration, compliance, evidence and traceability
- Workers: grievance and labour-rights visibility
The proposed governance framework assigns institutional responsibilities while emphasizing role-based access, audit trails, data protection and governed interoperability.
🚀 17. Why Is This Important for the Future of Automotive SMEs?
The platform is designed to connect compliance with the actual product and supply chain.
For an SME, this means its compliance record is not simply a collection of documents. It can become part of a structured digital record connected with its facility, suppliers, production activities and products.
For an international buyer, the model provides a mechanism for controlled access to product and compliance evidence.
For inspectors, it provides digital inspection and corrective-action workflows.
For institutions, it provides dashboards, indicators, risk information and aggregated reporting.
📝 18. Conclusion
The National Digital Compliance & Traceability Platform presented for the automotive sector is designed to bring SME formalization, compliance monitoring, due diligence, multi-tier supply-chain traceability, Digital Product Passport readiness, analytics and institutional interoperability into one digital ecosystem.
For automotive SMEs, the proposed app can provide a practical pathway from registration and compliance assessment to corrective actions, supplier traceability, product identification and export-readiness evidence.
The presentation's closing value proposition is that the platform is intended to make compliance visible, traceable and actionable, while supporting SMEs and Tier 1–4 suppliers through a secure and nationally governed architecture.
Important: This article describes the proposed/draft platform presented in the supplied presentation. Specific regulatory obligations, implementation dates, integrations and certification requirements should be verified against current official sources before being used for a specific business or export decision.
🏷️ Hashtags
#NationalCompliancePlatform #DigitalTraceability #AutomotiveSMEs #SMEs #PakistanAutomotive #SupplyChainTraceability #DigitalProductPassport #DPP #AutomotiveIndustry #Compliance #ExportReadiness #SMEFormalization #DueDiligence #SupplyChain #AutomotiveExports #PakistanExports #DigitalTransformation #PaceTechnologies #ILO #SMEDA #PAMA #EDB #PSQCA
0 -
Waqas Dar 7,113
Hazrat Yusuf (AS) – A complete Qur’anic and Tafsir biography covering his life, trials, patience, faith, forgiveness, and lessons from Surah Yusuf. Prophet Adam (AS) ➝ Prophet Idris (AS) ➝ Prophet Nuh (AS) ➝ Prophet Hud (AS) ➝ Prophet Salih (AS) ➝ Prophet Ibrahim (AS) ➝ Prophet Lut (AS) ➝ Prophet Ismail (AS) ➝ Prophet Ishaq (AS) ➝ Prophet Yaqub (AS) ➝ ★ Prophet Yusuf (AS) ➝ Prophet Ayyub (AS) ➝ Prophet Shuayb (AS) ➝ Prophet Musa (AS) ➝ Prophet Harun (AS) ➝ Prophet Dhul-Kifl (AS) ➝ Prophet Dawud (AS) ➝ Prophet Sulayman (AS) ➝ Prophet Ilyas (AS) ➝ Prophet Al-Yasa (AS) ➝ Prophet Yunus (AS) ➝ Prophet Zakariya (AS) ➝ Prophet Yahya (AS) ➝ Prophet Isa (AS) ➝ Prophet Muhammad ﷺ
Prophet Yusuf (AS) – Complete Qur’anic & Tafsir Biography / حضرت یوسف علیہ السلام – مکمل قرآنی و تفسیری زندگی
🧭 1. Introduction / تعارف
English: Prophet Yusuf (AS) was one of the noble prophets of Allah and the beloved son of Prophet Yaqub (AS). His life is one of the most detailed prophetic stories mentioned in the Qur’an, especially in Surah Yusuf. His story contains lessons of faith, patience, forgiveness, chastity, wisdom, leadership, and complete trust in Allah.
اردو: حضرت یوسف علیہ السلام اللہ تعالیٰ کے جلیل القدر نبی اور حضرت یعقوب علیہ السلام کے محبوب بیٹے تھے۔ آپ کی زندگی کا واقعہ قرآن مجید میں خاص طور پر سورۃ یوسف میں تفصیل کے ساتھ بیان ہوا ہے۔ آپ کی زندگی ایمان، صبر، پاکدامنی، حکمت، معافی، قیادت اور اللہ پر کامل بھروسے کے عظیم اسباق پر مشتمل ہے۔
Arabic: نَحْنُ نَقُصُّ عَلَيْكَ أَحْسَنَ الْقَصَصِ
Reference: Qur’an 12:3
👨👦 2. Blessed Family & Lineage / مبارک خاندان اور نسب
English: Prophet Yusuf (AS) belonged to a blessed prophetic family. He was the son of Prophet Yaqub (AS), the grandson of Prophet Ishaq (AS), and the great-grandson of Prophet Ibrahim (AS). His family was honored with prophethood and divine guidance.
اردو: حضرت یوسف علیہ السلام ایک مبارک نبوی خاندان سے تعلق رکھتے تھے۔ آپ حضرت یعقوب علیہ السلام کے بیٹے، حضرت اسحاق علیہ السلام کے پوتے اور حضرت ابراہیم علیہ السلام کے پڑپوتے تھے۔ آپ کا خاندان نبوت اور اللہ کی ہدایت سے عزت یافتہ خاندان تھا۔
Arabic: وَكَذَٰلِكَ يَجْتَبِيكَ رَبُّكَ وَيُعَلِّمُكَ مِن تَأْوِيلِ الْأَحَادِيثِ
Reference: Qur’an 12:6
🌙 3. The Beautiful Dream / خوبصورت خواب
English: Prophet Yusuf (AS) saw a remarkable dream in which he saw eleven stars, the sun, and the moon prostrating before him. Prophet Yaqub (AS) understood that the dream carried a special meaning and advised Yusuf (AS) not to tell his brothers about it.
اردو: حضرت یوسف علیہ السلام نے ایک عظیم خواب دیکھا جس میں انہوں نے گیارہ ستاروں، سورج اور چاند کو اپنے سامنے سجدہ کرتے دیکھا۔ حضرت یعقوب علیہ السلام نے سمجھ لیا کہ اس خواب میں ایک خاص اشارہ ہے اور انہوں نے حضرت یوسف علیہ السلام کو ہدایت کی کہ یہ خواب اپنے بھائیوں کو نہ بتائیں۔
Arabic: إِنِّي رَأَيْتُ أَحَدَ عَشَرَ كَوْكَبًا وَالشَّمْسَ وَالْقَمَرَ رَأَيْتُهُمْ لِي سَاجِدِينَ
Reference: Qur’an 12:4
💔 4. The Well – Betrayal by His Brothers / کنواں اور بھائیوں کی جدائی
English: Prophet Yusuf’s (AS) brothers became jealous of the love their father showed toward him. They planned to take Yusuf (AS) away and eventually threw him into a well. They later returned to their father with a false story and Yusuf’s shirt covered with false blood.
اردو: حضرت یوسف علیہ السلام کے بھائی اپنے والد کی محبت کی وجہ سے حسد میں مبتلا ہوگئے۔ انہوں نے حضرت یوسف علیہ السلام کو اپنے ساتھ لے جا کر کنویں میں ڈال دیا۔ پھر وہ جھوٹی کہانی بنا کر حضرت یعقوب علیہ السلام کے پاس واپس آئے اور حضرت یوسف علیہ السلام کی قمیص کو جھوٹے خون سے آلودہ کر دیا۔
Arabic: قَالُوا يَا أَبَانَا إِنَّا ذَهَبْنَا نَسْتَبِقُ وَتَرَكْنَا يُوسُفَ عِندَ مَتَاعِنَا فَأَكَلَهُ الذِّئْبُ
Reference: Qur’an 12:17
⛓️ 5. Egypt – From Slavery to Trial / مصر اور آزمائش
English: Yusuf (AS) was found by travelers and taken to Egypt. He was sold and came into the household of a prominent Egyptian official. Despite his difficult circumstances, Allah protected him and prepared him for a greater purpose.
اردو: حضرت یوسف علیہ السلام کو ایک قافلے نے کنویں سے نکالا اور مصر لے گیا۔ وہاں انہیں فروخت کر دیا گیا اور وہ ایک بااثر مصری شخص کے گھر میں پہنچے۔ مشکل حالات کے باوجود اللہ تعالیٰ نے حضرت یوسف علیہ السلام کی حفاظت فرمائی اور انہیں ایک بڑے مقصد کے لیے تیار کیا۔
Arabic: وَشَرَوْهُ بِثَمَنٍ بَخْسٍ دَرَاهِمَ مَعْدُودَةٍ
Reference: Qur’an 12:20
🛡️ 6. Chastity & Temptation / پاکدامنی اور آزمائش
English: One of the greatest tests in Prophet Yusuf’s (AS) life came when he was tempted by the wife of the Egyptian official. Yusuf (AS) refused the temptation and chose obedience to Allah over worldly desire. His response demonstrated extraordinary chastity and fear of Allah.
اردو: حضرت یوسف علیہ السلام کی زندگی کی ایک بڑی آزمائش اس وقت آئی جب مصر کے بااثر شخص کی بیوی نے انہیں گناہ کی طرف بلایا۔ حضرت یوسف علیہ السلام نے گناہ سے انکار کیا اور دنیاوی خواہش کے مقابلے میں اللہ کی اطاعت کو ترجیح دی۔ یہ واقعہ آپ کی پاکدامنی اور اللہ کے خوف کی عظیم مثال ہے۔
Arabic: مَعَاذَ اللَّهِ إِنَّهُ رَبِّي أَحْسَنَ مَثْوَايَ
Reference: Qur’an 12:23
⛓️ 7. Prison – Patience During Hardship / قید خانہ اور صبر
English: Although Prophet Yusuf (AS) was innocent, he was imprisoned. Even in prison, he remained patient and continued calling people toward the worship of Allah. He also interpreted the dreams of two prisoners by the knowledge Allah had given him.
اردو: بے گناہ ہونے کے باوجود حضرت یوسف علیہ السلام کو قید کر دیا گیا۔ قید خانے میں بھی آپ نے صبر کا دامن نہیں چھوڑا اور لوگوں کو اللہ کی عبادت کی دعوت دیتے رہے۔ اللہ تعالیٰ کے عطا کردہ علم سے آپ نے دو قیدیوں کے خوابوں کی تعبیر بھی بیان فرمائی۔
Arabic: يَا صَاحِبَيِ السِّجْنِ أَأَرْبَابٌ مُّتَفَرِّقُونَ خَيْرٌ أَمِ اللَّهُ الْوَاحِدُ الْقَهَّارُ
Reference: Qur’an 12:39
👑 8. The King’s Dream & Rise to Leadership / بادشاہ کا خواب اور منصب
English: When the king of Egypt saw a troubling dream, Yusuf (AS) interpreted it accurately. He explained that seven years of abundance would be followed by seven difficult years of famine. His wisdom and knowledge eventually led to his appointment over the storehouses of Egypt.
اردو: جب مصر کے بادشاہ نے ایک پریشان کن خواب دیکھا تو حضرت یوسف علیہ السلام نے اس کی درست تعبیر بیان فرمائی۔ آپ نے بتایا کہ سات سال خوشحالی کے ہوں گے اور اس کے بعد سات سخت قحط کے سال آئیں گے۔ آپ کی حکمت اور علم کی وجہ سے آخرکار آپ کو مصر کے خزانوں اور انتظام کی ذمہ داری دی گئی۔
Arabic: اجْعَلْنِي عَلَىٰ خَزَائِنِ الْأَرْضِ إِنِّي حَفِيظٌ عَلِيمٌ
Reference: Qur’an 12:55
🤝 9. Reunion with His Brothers / بھائیوں سے دوبارہ ملاقات
English: During the years of famine, Yusuf’s (AS) brothers came to Egypt seeking food. They did not recognize Yusuf (AS), but he recognized them. Allah eventually brought the family together and fulfilled the meaning of Yusuf’s childhood dream.
اردو: قحط کے سالوں میں حضرت یوسف علیہ السلام کے بھائی غلہ حاصل کرنے کے لیے مصر آئے۔ وہ حضرت یوسف علیہ السلام کو پہچان نہ سکے، لیکن حضرت یوسف علیہ السلام نے انہیں پہچان لیا۔ اللہ تعالیٰ نے آخرکار پورے خاندان کو دوبارہ ملا دیا اور حضرت یوسف علیہ السلام کے بچپن کے خواب کی تعبیر پوری ہوئی۔
❤️ 10. Forgiveness of His Brothers / بھائیوں کو معاف کرنا
English: When Yusuf (AS) finally revealed his identity to his brothers, he did not seek revenge. Instead, he forgave them and reminded them of Allah’s mercy. His forgiveness became one of the greatest lessons of his life.
اردو: جب حضرت یوسف علیہ السلام نے اپنے بھائیوں پر اپنی حقیقت ظاہر کی تو انہوں نے بدلہ لینے کے بجائے انہیں معاف کر دیا۔ آپ نے ان کے لیے اللہ کی رحمت کی امید دلائی۔ آپ کی یہ معافی آپ کی زندگی کے عظیم ترین اسباق میں سے ایک ہے۔
Arabic: لَا تَثْرِيبَ عَلَيْكُمُ الْيَوْمَ ۖ يَغْفِرُ اللَّهُ لَكُمْ
Reference: Qur’an 12:92
🌟 11. Fulfillment of the Dream / خواب کی تکمیل
English: After many years of trials, Prophet Yusuf (AS) was reunited with his parents and family. His childhood dream was fulfilled, and he recognized that Allah had been guiding his life through every hardship and every stage.
اردو: کئی سال کی آزمائشوں کے بعد حضرت یوسف علیہ السلام اپنے والدین اور خاندان سے دوبارہ ملے۔ آپ کا بچپن کا خواب پورا ہوا اور آپ نے محسوس کیا کہ اللہ تعالیٰ ہر آزمائش اور زندگی کے ہر مرحلے میں آپ کی رہنمائی فرماتا رہا۔
Arabic: يَا أَبَتِ هَٰذَا تَأْوِيلُ رُؤْيَايَ مِن قَبْلُ قَدْ جَعَلَهَا رَبِّي حَقًّا
Reference: Qur’an 12:100
📖 12. Complete Tafsir Narrative / مکمل تفسیری بیان
ENGLISH:
Prophet Yusuf (AS) was a symbol of patience, purity, wisdom, forgiveness, and complete trust in Allah. His life moved through many stages: a beloved child, a victim of jealousy, a young man in a foreign land, a prisoner, and finally a trusted leader in Egypt.
Throughout every stage, Yusuf (AS) remained faithful to Allah. He refused temptation, remained patient during imprisonment, used the knowledge Allah gave him, and served people with wisdom and justice.
When he finally gained authority, he did not use his power for revenge. Instead, he forgave the brothers who had harmed him. His story shows how Allah can bring good outcomes from circumstances that initially appear full of hardship.
The story of Yusuf (AS) teaches believers that patience, righteousness, forgiveness, and trust in Allah can transform trials into opportunities for goodness and guidance.
URDU:
حضرت یوسف علیہ السلام صبر، پاکدامنی، حکمت، معافی اور اللہ پر کامل بھروسے کی عظیم مثال ہیں۔ آپ کی زندگی نے کئی مراحل دیکھے: ایک محبوب بیٹے سے لے کر بھائیوں کے حسد، کنویں کی آزمائش، مصر میں زندگی، قید خانے اور پھر مصر میں ایک اہم منصب تک۔
زندگی کے ہر مرحلے میں حضرت یوسف علیہ السلام اللہ تعالیٰ پر ایمان کے ساتھ قائم رہے۔ آپ نے گناہ سے انکار کیا، قید میں صبر کیا، اللہ کے عطا کردہ علم کو استعمال کیا اور حکمت کے ساتھ لوگوں کی خدمت کی۔
جب اللہ تعالیٰ نے آپ کو اقتدار عطا فرمایا تو آپ نے اپنے بھائیوں سے بدلہ لینے کے بجائے انہیں معاف کر دیا۔ آپ کی زندگی ہمیں سکھاتی ہے کہ اللہ تعالیٰ مشکلات کے اندر بھی خیر کے راستے پیدا فرما سکتا ہے۔
حضرت یوسف علیہ السلام کا واقعہ ہمیں صبر، نیکی، پاکدامنی، معافی اور اللہ پر بھروسے کا عظیم سبق دیتا ہے۔
ARABIC (QUR’ANIC REFERENCES):
نَحْنُ نَقُصُّ عَلَيْكَ أَحْسَنَ الْقَصَصِ
مَعَاذَ اللَّهِ إِنَّهُ رَبِّي أَحْسَنَ مَثْوَايَ
اجْعَلْنِي عَلَىٰ خَزَائِنِ الْأَرْضِ إِنِّي حَفِيظٌ عَلِيمٌ
لَا تَثْرِيبَ عَلَيْكُمُ الْيَوْمَ ۖ يَغْفِرُ اللَّهُ لَكُمْ
📖 13. Lessons / اسباق
✔ Patience during hardship ✔ Trust in Allah ✔ Chastity and self-control ✔ Forgiveness ✔ Wisdom and leadership ✔ Never lose hope ✔ Allah’s plan is greater
✔ مشکل میں صبر ✔ اللہ پر بھروسہ ✔ پاکدامنی اور نفس پر قابو ✔ معافی ✔ حکمت اور قیادت ✔ امید نہ چھوڑنا ✔ اللہ کی تدبیر سب سے بہتر ہے
📖 14. Conclusion / نتیجہ
Prophet Yusuf (AS) is a timeless example of patience, purity, forgiveness, wisdom, and unwavering trust in Allah. His story reminds believers that hardship can be followed by ease and that Allah’s wisdom is present even when we cannot understand the purpose of a trial.
حضرت یوسف علیہ السلام صبر، پاکدامنی، معافی، حکمت اور اللہ پر کامل بھروسے کی ہمیشہ زندہ مثال ہیں۔ آپ کی زندگی ہمیں یاد دلاتی ہے کہ مشکل کے بعد آسانی آ سکتی ہے اور اللہ تعالیٰ کی حکمت ہر آزمائش میں موجود ہوتی ہے، چاہے انسان اس وقت اسے سمجھ نہ سکے۔
🌿 FundayForum.com
0 -
ZD Gold Fish 83
Top 20 highest run scorers in ODI cricket history, featuring legendary batters and the all-time leaders in One Day International runs. 🏏 Top 20 Highest Run Scorers in ODI Cricket History
🏏 Introduction
One Day International cricket has given fans some of the greatest batsmen in the history of the sport. Over the decades, legendary players have produced thousands of runs while representing their countries in hundreds of matches.
From Sachin Tendulkar's incredible longevity to Virat Kohli's remarkable consistency, the all-time ODI run-scoring list features some of cricket's most recognizable names.
This article looks at the top 20 highest run scorers in men's ODI cricket history, along with their innings, batting averages, ducks and international career span.
📊 Top 20 Highest ODI Run Scorers
Rank Player ODI Runs Innings Average Ducks Career 1 🇮🇳 Sachin Tendulkar 18,426 452 44.83 20 1989–2012 2 🇮🇳 Virat Kohli 14,941 302 58.59 18 2008–Present 3 🇱🇰 Kumar Sangakkara 14,234 380 41.99 15 2000–2015 4 🇦🇺 Ricky Ponting 13,704 365 42.04 20 1995–2012 5 🇱🇰 Sanath Jayasuriya 13,430 433 32.36 34 1989–2011 6 🇱🇰 Mahela Jayawardene 12,650 418 33.38 28 1998–2015 7 🇮🇳 Rohit Sharma 11,895 280 48.95 16 2007–Present 8 🇵🇰 Inzamam-ul-Haq 11,739 350 39.53 20 1991–2007 9 🇿🇦 Jacques Kallis 11,579 314 44.36 17 1996–2014 10 🇮🇳 Sourav Ganguly 11,363 300 41.02 16 1992–2007 11 🇮🇳 Rahul Dravid 10,889 318 39.17 13 1996–2011 12 🇮🇳 MS Dhoni 10,773 297 50.58 10 2004–2019 13 🏝️ Chris Gayle 10,480 294 37.83 25 1999–2019 14 🏝️ Brian Lara 10,405 289 40.49 16 1990–2007 15 🇱🇰 Tillakaratne Dilshan 10,290 303 39.27 11 1999–2016 16 🇵🇰 Mohammad Yousuf 9,720 273 41.72 15 1998–2010 17 🇦🇺 Adam Gilchrist 9,619 279 35.89 19 1996–2008 18 🇿🇦 AB de Villiers 9,577 218 53.50 7 2005–2018 19 🇮🇳 Mohammad Azharuddin 9,378 308 36.92 9 1985–2000 20 🇱🇰 Aravinda de Silva 9,284 296 34.90 17 1984–2003
🥇 Sachin Tendulkar – The All-Time ODI Run Leader
🇮🇳 Sachin Tendulkar remains at the top of the ODI run-scoring chart with 18,426 runs.
His ODI career stretched from 1989 to 2012, covering more than two decades of international cricket. Tendulkar played 452 ODI innings and maintained a batting average of 44.83.
His enormous run tally reflects not only his batting ability but also his extraordinary longevity at the international level.
🇮🇳 Virat Kohli – Exceptional ODI Consistency
Virat Kohli's record is particularly notable for his 58.59 batting average.
With 14,941 ODI runs, Kohli is among the most prolific run scorers in the history of the format. His record has been built around consistency, frequent big scores and an ability to perform under pressure.
His average is one of the standout statistics among the leading ODI run scorers.
🇱🇰 Sri Lanka's ODI Batting Legends
Sri Lanka has several representatives among the highest run scorers.
Kumar Sangakkara, Sanath Jayasuriya and Mahela Jayawardene occupy three positions near the top of the list.
Sangakkara accumulated 14,234 runs, Jayasuriya scored 13,430, while Jayawardene finished with 12,650 ODI runs.
Their records reflect the strength of Sri Lanka's batting during one of the country's most successful periods in international cricket.
🇮🇳 India's Dominance in the Top 20
India has a particularly strong presence on the all-time list.
Alongside Tendulkar and Kohli, the top 20 includes Rohit Sharma, Sourav Ganguly, Rahul Dravid, MS Dhoni and Mohammad Azharuddin.
These players represent different generations of Indian ODI cricket, from the 1980s and 1990s through to the modern era.
🇵🇰 Pakistan's Leading ODI Run Scorers
Pakistan is represented by two legendary batsmen in the top 20.
🇵🇰 Inzamam-ul-Haq scored 11,739 ODI runs during his international career from 1991 to 2007.
🇵🇰 Mohammad Yousuf finished with 9,720 ODI runs, maintaining an average of 41.72.
Both players were important parts of Pakistan's batting line-ups during their respective eras.
📈 Runs vs Batting Average
Total runs and batting average measure different aspects of a player's ODI career.
A high run total generally reflects a combination of longevity, opportunities and sustained performance. Batting average, meanwhile, shows how many runs a batter scored per dismissal.
For example, AB de Villiers scored 9,577 ODI runs with a remarkable average of 53.50. Virat Kohli's average of 58.59 is even higher.
On the other hand, players such as Sanath Jayasuriya accumulated huge career totals while playing an aggressive style that naturally involved greater risk.
🦆 What Does "Ducks" Mean in Cricket?
A duck occurs when a batter is dismissed without scoring a run.
Ducks are included in the table because they provide another interesting statistic when comparing long ODI careers.
Sanath Jayasuriya, for example, played 433 ODI innings and recorded 34 ducks, while MS Dhoni had 10 ducks across 297 innings.
A high number of ducks does not necessarily indicate poor batting because players who have played hundreds of international innings naturally have more opportunities to record both very high scores and ducks.
🌍 A Record Spanning Generations
The players on this list span several generations of ODI cricket.
From Sachin Tendulkar and Brian Lara to Virat Kohli and Rohit Sharma, these batsmen have played during very different periods, with changes in equipment, playing conditions, rules and batting strategies.
Yet their names remain connected by one achievement: scoring thousands of runs for their countries in ODI cricket.
🔎 Quick ODI Batting Facts
-
🥇 Highest career ODI runs: Sachin Tendulkar — 18,426
-
🇮🇳 Virat Kohli's ODI runs: 14,941
-
🇱🇰 Highest Sri Lankan: Kumar Sangakkara — 14,234
-
🇵🇰 Highest Pakistani in this list: Inzamam-ul-Haq — 11,739
-
🇿🇦 AB de Villiers: 9,577 runs at a 53.50 average
-
🏏 Most players represented: India
-
📊 Players listed: 20
-
🌍 Format: Men's One Day International cricket
❓ Frequently Asked Questions
Who has scored the most runs in ODI cricket?
Sachin Tendulkar holds the highest career ODI run total in the table, with 18,426 runs.
Who has the highest batting average among these players?
Virat Kohli has the highest listed batting average at 58.59.
Who is the highest-scoring Pakistani batsman on this list?
Inzamam-ul-Haq is the highest-ranked Pakistani player in this top 20, with 11,739 ODI runs.
How many ODI runs did Sachin Tendulkar score?
Sachin Tendulkar scored 18,426 runs in ODI cricket.
How many ODI runs did Virat Kohli score?
Virat Kohli has 14,941 ODI runs in the figures listed above.
Who scored more ODI runs, Sachin Tendulkar or Virat Kohli?
Sachin Tendulkar has the higher career ODI run total, while Virat Kohli has the higher batting average among the two.
What is a duck in cricket?
A duck means a batter was dismissed without scoring any runs.
Why are innings and average included with total runs?
Total runs show overall career production, while innings and average provide additional context about how those runs were accumulated.
🏏 Final Thoughts
The all-time ODI run-scoring list is a record of consistency, longevity and remarkable batting performances.
Sachin Tendulkar's 18,426 runs remain a huge career achievement, while players such as Virat Kohli, Kumar Sangakkara, Ricky Ponting, Jayasuriya, Jayawardene and Rohit Sharma have also established themselves among the most productive ODI batsmen in cricket history.
For cricket fans, these numbers are more than statistics — they represent decades of memorable innings, major tournaments and performances that helped define different eras of ODI cricket.
Who is your favorite ODI batsman from this list? Share your choice and your favorite innings in the comments below.
FundayForum category: 🏏 Cricket Talk
tags:
Cricket, ODI, ODI Records, Cricket Records, Sachin Tendulkar, Virat Kohli, Rohit Sharma, Babar Azam, Pakistan Cricket, India Cricket, Sri Lanka Cricket, Cricket Statistics0 -
-
Waqas Dar 7,113
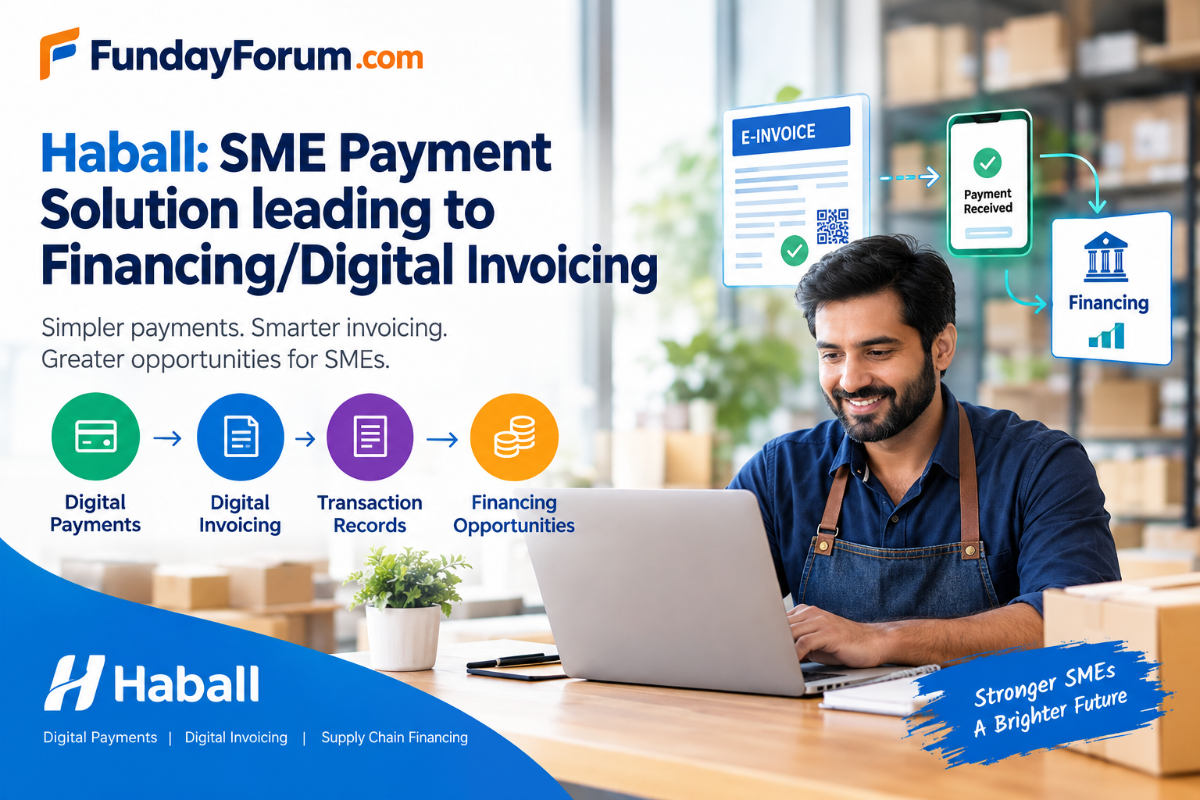
A visual overview of how Haball can connect SME digital payments and e-invoicing with transaction records and supply-chain financing opportunities in Pakistan. Haball: How SME Payments Can Lead to Digital Invoicing and Financing
For a small business, getting paid on time can be just as important as making a sale.
A distributor may have plenty of customers but still struggle with cash flow because buyers take weeks to settle their invoices. A manufacturer may have confirmed orders but need additional money to purchase raw materials. A retailer may have regular sales but keep most of its records manually.
These are everyday problems for small and medium-sized businesses.
This is where digital financial services are becoming increasingly important in Pakistan. Haball is one of the fintech companies working in this area, with solutions aimed at digitizing business payments, invoicing and supply-chain financing.
The interesting part is that these services are connected. A digital payment is not only a way of transferring money. When it is linked with an invoice and a business transaction, it can also create a useful record of the company's commercial activity. Over time, that information can potentially help an eligible business access financing.
In simple terms, the idea can be understood as:
Invoice → Payment → Digital Record → Better Cash-Flow Information → Potential Financing
What Is Haball?
Haball is a Pakistan-based B2B fintech company that focuses on digitalizing financial transactions between businesses.
Its services are aimed at different participants in a supply chain, including companies, manufacturers, distributors and retailers. Instead of businesses handling orders, invoices, payments and reconciliation through completely separate manual processes, Haball's approach is to bring more of these activities into a digital environment.
This matters because business payments are rarely isolated transactions.
When a company sells goods to a distributor, there is normally an order, an invoice, delivery of the goods and eventually a payment. If the payment is delayed, the seller may need working capital to continue operating.
A digital platform can connect some of these steps and make the transaction easier to track.
Why SME Payments Matter
Small and medium-sized businesses often operate on tight cash-flow cycles.
Imagine a distributor that purchases goods for PKR 10 million and sells them to retailers for PKR 12 million. On paper, the business has generated a healthy margin.
But what happens if the retailers pay after 30 or 60 days?
The distributor still has to purchase its next batch of inventory. It also has salaries, transportation, rent and other expenses to cover.
The business therefore has money tied up in receivables.
This is one reason working capital is so important for SMEs.
A digital payment system cannot remove the underlying cash-flow problem, but it can make the movement of money easier to track and reconcile. More importantly, when invoices and payments are digitally recorded, the business can build a clearer history of its transactions.
From Paper Invoices to Digital Invoicing
In many businesses, invoicing remains a surprisingly manual process.
An invoice may be prepared in accounting software, printed, emailed or sent through a messaging application. Someone then has to check whether the customer has paid and update the company's records.
When a business handles a small number of invoices, this may be manageable.
The problem becomes much bigger when hundreds or thousands of invoices are generated every month.
Digital invoicing can simplify this process.
Haball's Wasal solution is designed around electronic invoicing and invoice registration. According to Haball, Wasal can integrate with corporate ERP systems and supports invoice registration with the Federal Board of Revenue (FBR), along with invoice validation and QR-code functionality.
For a business, the benefit is not simply having a PDF instead of a paper invoice.
The bigger benefit is having structured information that can be connected with the payment and accounting process.
Why the Invoice Matters
An invoice provides evidence that a commercial transaction has taken place.
Suppose a Pakistani manufacturer supplies hospital equipment worth PKR 5 million to a distributor.
The manufacturer issues an invoice for PKR 5 million.
The distributor agrees to pay after 45 days.
The manufacturer now has a receivable of PKR 5 million.
If the invoice, customer relationship and subsequent payment are recorded digitally, there is a much clearer trail of the transaction.
That information can be useful to the business itself.
It can also potentially become relevant when the business seeks financing.
This is one of the reasons digital invoicing and digital payments can work together rather than being treated as two completely separate technologies.
How Financing Enters the Picture
The financing opportunity becomes easier to understand when we look at a normal SME cash-flow cycle.
A company sells products today.
The customer agrees to pay after 30 days.
The company needs money tomorrow to purchase more inventory.
The company therefore has a timing problem.
It has made the sale, but the cash has not yet arrived.
Supply-chain financing is designed to address situations like this, depending on the specific financing arrangement.
Haball's Wisaaq platform is focused on digital supply-chain financing and connects businesses and financial institutions through a digital process.
The basic concept is that eligible commercial transactions can form part of a financing workflow.
However, there is an important point that business owners should understand:
Using Haball or issuing digital invoices does not automatically mean that an SME will receive financing.
Financing remains subject to the relevant bank or financing institution's requirements, credit assessment, documentation, transaction eligibility and other applicable conditions.
Digital records can support the assessment; they do not replace it.
A Simple Example
Consider a distributor that supplies consumer products to 200 retailers.
The distributor generates PKR 15 million in invoices every month.
Its customers normally pay between 30 and 45 days after receiving their goods.
At the same time, the distributor needs to pay suppliers much earlier.
This creates a recurring working-capital gap.
If the distributor uses digital invoicing and payments, its business records can show:
-
How much it invoices.
-
Which customers are purchasing.
-
How frequently payments are received.
-
How much remains outstanding.
-
How the business's collections change over time.
That information does not guarantee financing, but it gives the business a much more organized financial history.
If the distributor qualifies for a supply-chain financing product, this transaction history may become part of the financing assessment.
This is the real connection between payments and financing.
Haball and Supply-Chain Financing
Haball's approach is particularly relevant to businesses that operate within established supply chains.
A supply chain normally involves several parties:
Manufacturer → Distributor → Retailer → Customer
Money moves through the same network in the opposite direction.
If financial information from these transactions is digitized, there is an opportunity to create a more connected system.
The manufacturer can have better information about sales.
The distributor can manage payments and invoices more efficiently.
The bank or financing institution can potentially receive more structured transaction information.
The retailer can receive and settle invoices through digital channels.
The result is a more connected financial process.
Wisaaq and SME Financing
Haball describes Wisaaq as a digital supply-chain financing platform, including an Islamic financing offering.
The platform is designed to connect corporate businesses, SMEs and banks and digitize parts of the financing process.
This is particularly interesting for Pakistan because many businesses are looking for financing structures that comply with Islamic finance principles.
However, businesses should always examine the actual financing agreement, pricing, repayment terms and Shariah structure offered by the relevant financial institution before making a financing decision.
A platform can provide the technology, but the actual financing arrangement still needs to be understood on its own terms.
The Role of Banks
Fintech companies do not necessarily have to replace traditional banks.
In fact, one of the more useful models is cooperation between the two.
A fintech can provide the technology and digital workflow.
A bank can provide the financing.
The SME provides the underlying business activity and transaction information.
This creates a three-way relationship:
SME + Fintech Platform + Financial Institution
Haball has announced partnerships with financial institutions in Pakistan in connection with digital supply-chain financing.
This type of partnership is important because SMEs ultimately need access not only to technology but also to actual financial products.
Digital Records Can Help a Business Even Without Financing
There is sometimes too much emphasis on the financing side of fintech.
An SME does not need to take a loan for digital payments and invoicing to be useful.
Better records alone can make a significant difference.
A business owner can more easily identify:
-
Which customers have paid.
-
Which invoices are overdue.
-
How much money is expected next week.
-
Which customers purchase most frequently.
-
How much is being paid to suppliers.
-
Whether sales are increasing or declining.
This information can help management make better decisions.
For a growing company, knowing its actual cash position can be more valuable than simply knowing its total sales.
Digital Payments and Business Transparency
Cash has always been an important part of commerce in Pakistan.
But cash transactions can be difficult to track at scale.
When payments move through digital channels, there is an electronic record of the transaction.
This can improve transparency and make reconciliation easier.
For example, if a business receives 100 customer payments in a month, manually matching every payment with the correct invoice can take considerable time.
A digital workflow can potentially reduce this administrative burden.
The result is not only convenience.
It can also give the business a more reliable understanding of its financial position.
What Does This Mean for a Small Business Owner?
For an SME owner, the biggest takeaway is that digitalization should not be viewed simply as "using an online payment service."
It is about creating a connected financial process.
Instead of:
Sale → Paper Invoice → Manual Entry → Bank Payment → Manual Reconciliation
the process can move toward:
Sale → Digital Invoice → Digital Payment → Digital Record → Reconciliation
And if the business needs working capital:
Digital Transaction History → Financing Assessment → Potential Supply-Chain Finance
That is a much broader proposition.
What SMEs Should Check Before Choosing a Financing Solution
Businesses should not choose a financial service simply because it promises fast financing.
Before entering into any arrangement, an SME should understand:
-
What financing amount is available?
-
What is the total cost of financing?
-
What fees are charged?
-
What is the repayment period?
-
Is collateral or a guarantee required?
-
Which financial institution provides the financing?
-
What invoices or transactions qualify?
-
What documentation is required?
-
What happens if a customer does not pay?
-
What are the applicable terms and conditions?
These questions are important because financing should solve a cash-flow problem without creating a larger financial burden.
The Importance of FBR E-Invoicing
Electronic invoicing is also becoming increasingly relevant because Pakistan's tax system is moving toward greater digitalization.
Businesses need to understand their applicable FBR requirements and whether they fall within the relevant e-invoicing rules.
Haball's Wasal solution is positioned around electronic invoicing and integration with FBR requirements.
For businesses that need to maintain compliant digital records, this type of technology can potentially reduce manual processes.
However, companies should always verify their specific tax obligations with FBR or a qualified tax professional because requirements can differ depending on the taxpayer and nature of business.
Is Haball Only Useful for Large Companies?
No.
Although large companies can benefit significantly from supply-chain digitization, the SME side is an important part of the model.
A large company may have an established ERP system and finance department.
A smaller distributor may not have the same level of infrastructure.
Digital platforms can potentially give smaller businesses access to tools that would otherwise require significant investment in technology and administrative resources.
The actual availability of a particular product, however, depends on Haball's current services, participating partners and the business's eligibility.
The Bigger Opportunity
The bigger story behind Haball is the gradual movement from transaction-based finance to data-supported business finance.
In the traditional model, a bank may see a company's financial position mainly through periodic statements and documents.
In a more digital model, business activity can generate information continuously.
Invoices show sales.
Payments show collections.
Transaction history shows patterns.
Supply-chain relationships provide additional context.
This does not eliminate the need for traditional financial analysis, but it can potentially give lenders a more complete picture of an SME.
For small businesses that have historically struggled to demonstrate their financial strength, that can be meaningful.
Final Thoughts
Haball's SME payment solution is best understood as part of a wider shift in the way businesses manage money.
The payment itself is only one piece of the puzzle.
When payments are connected with invoices, accounting records and supply-chain activity, they can create a much clearer picture of how a business operates.
Digital invoicing can make transactions easier to document.
Digital payments can make collections easier to track.
Structured transaction records can improve financial visibility.
And, for eligible businesses, that information can potentially support access to supply-chain financing.
The journey can therefore be summarized simply:
Business Sale → Digital Invoice → Digital Payment → Transaction Record → Better Financial Visibility → Potential Financing
For Pakistan's SMEs, this transition has practical significance. A business that keeps accurate digital records is in a stronger position to understand its own cash flow, manage customers and suppliers, meet applicable compliance requirements and demonstrate its commercial activity to potential financial partners.
Haball is one example of how fintech is attempting to connect these different parts of the business cycle.
The real value will ultimately depend on how effectively SMEs adopt these tools, how well financial institutions use the resulting information, and whether digital financing products remain transparent, affordable and suitable for the businesses using them.
For an SME owner, the goal should not simply be to "go digital."
The goal should be to build a better documented, better managed and financially visible business.
0 -
-
Waqas Dar 7,113
Looking for a complete guide on how to register with GCCI in Gujranwala? The Gujranwala Chamber of Commerce & Industry (GCCI) membership process involves checking your business eligibility, preparing the required legal and tax documents, selecting the appropriate membership class, completing the GCCI membership application form, submitting the documents for verification and paying the applicable membership fee.
This GCCI registration guide 2026 explains the complete process in simple steps for sole proprietors, partnerships, AOPs, private limited companies, manufacturers, traders, importers, exporters and service providers. You will also find the latest GCCI membership fees, required documents, Associate and Corporate membership information, registration flow chart, renewal requirements, common mistakes and frequently asked questions.
If you are planning to obtain GCCI membership in Gujranwala, preparing your documents correctly before submitting your application can help make the registration process smoother and reduce delays caused by incomplete or inconsistent information.
### FAQ Section
Frequently Asked Questions About GCCI Registration
1. What is GCCI?
GCCI stands for Gujranwala Chamber of Commerce & Industry. It is a Chamber representing the business and industrial community of Gujranwala and supporting commercial, industrial and trade-related activities.
2. Who can apply for GCCI membership?
Eligible businesses operating within the GCCI jurisdiction can apply. This may include sole proprietorships, partnerships, AOPs, private limited companies, limited companies, manufacturers, traders, importers, exporters and service providers, subject to the applicable GCCI requirements.
3. What documents are required for GCCI membership?
The required documents depend on your business structure. Common documents include the GCCI membership application form, CNIC, photograph, NTN, sales tax registration where applicable, business registration documents, business address and information about your business nature and products or services.
4. What is the difference between Associate and Corporate GCCI membership?
GCCI has Associate and Corporate membership classes. Associate membership is generally for businesses that do not qualify for Corporate Class, while Corporate membership is available to businesses meeting GCCI's specific Corporate Class criteria.
5. How much does GCCI membership cost?
The membership fee depends on the membership class and the period in which the application is submitted. GCCI's published fee schedule effective from 16 December 2025 lists different fees for Associate and Corporate membership. Applicants should confirm the current fee with GCCI before making payment.
6. Do I need NTN for GCCI membership?
Yes. NTN and other relevant tax-registration information form an important part of the GCCI membership documentation. Additional tax documents may be required depending on your business structure and activities.
7. Is Sales Tax Registration required for GCCI membership?
Sales Tax Registration is required where applicable. The exact requirement can depend on the nature of the business and the membership class. Businesses should confirm their specific requirements with GCCI before applying.
8. Do I need a proposer and seconder for GCCI membership?
GCCI's published membership requirements provide for a new membership application to be proposed and seconded by existing members where applicable. Applicants should confirm the current requirements with the GCCI Membership Department.
9. How do I apply for GCCI membership?
The general process is:
Check eligibility → Prepare documents → Select membership class → Complete application form → Arrange proposer/seconder where applicable → Submit application → GCCI verification → Pay fee → Approval → Receive membership certificate and card.
10. Can I register for GCCI membership online?
GCCI provides an online registration section on its website, but the current website indicates that the online registration facility is still listed as “Coming Soon.” Therefore, applicants should confirm the current submission procedure directly with GCCI before relying on online registration.
11. How long does GCCI membership registration take?
The processing time can vary depending on the completeness of the application, verification requirements and any deficiencies in the submitted documents. To avoid unnecessary delays, submit a complete and accurate application and respond promptly if GCCI requests additional information.
12. What happens if my GCCI application has missing documents?
GCCI may require the applicant to provide missing or corrected documents before the application can be completed. It is therefore recommended to prepare a complete document file and ensure that the information matches your official business and tax records.
13. Do manufacturers need GCCI membership?
Manufacturers operating within the applicable GCCI jurisdiction can apply for membership if they meet the relevant requirements. Manufacturers should provide accurate information about their manufacturing activities and products.
14. Can exporters and importers become GCCI members?
Yes, eligible importers and exporters can apply for GCCI membership. Applicants should clearly mention their import or export activities and provide the relevant business and tax documentation.
15. When does GCCI membership need to be renewed?
GCCI membership is subject to annual renewal according to the Chamber's applicable rules. GCCI's published membership information states that the subscription deadline is 31 March each year.
16. What are the benefits of GCCI membership?
GCCI membership can provide businesses with opportunities for networking, business representation, trade-related activities, seminars, business events, business information and other Chamber-related services.
17. How can I verify my GCCI membership?
GCCI provides a members-verification facility through which membership information can be checked using the relevant membership details.
18. Where can I get the GCCI membership form?
The GCCI website provides a Membership Forms section where applicants can access the relevant membership forms and information. Always use the latest version of the form available from GCCI.
19. What should I write as my business nature in the GCCI application?
You should provide a clear and accurate description of your actual business activity. For example, instead of simply writing “General Trading,” you can specify the products or services you trade, manufacture, import or export.
20. What should I do before visiting GCCI for registration?
Prepare your complete application file, including your GCCI form, CNIC, photograph, NTN, sales tax documents where applicable, business registration documents, business address details, business nature and any required proposer/seconder information. Also confirm the latest GCCI fee and submission requirements before visiting.
GCCI Registration – Quick Answer
If you want to register with GCCI, the process can be summarized as:
1. Check Eligibility
↓
2. Prepare Legal & Tax Documents
↓
3. Select Associate or Corporate Class
↓
4. Complete GCCI Membership Form
↓
5. Arrange Proposer & Seconder Where Applicable
↓
6. Submit Application
↓
7. GCCI Verification
↓
8. Pay Applicable Fee
↓
9. Membership Approval
↓
10. Receive GCCI Certificate & Membership Card
Final Tip: GCCI requirements, forms and fees can change. Always confirm the latest information directly with the Gujranwala Chamber of Commerce & Industry before submitting your application or paying any fee.
Related Business, Import, Export & Tax Guides
If you are registering with GCCI and want to learn more about export procedures, import/export compliance, tax requirements and trade facilitation in Pakistan, these related guides may also be useful:
🔹 GCCI Membership Registration
How to Register with GCCI in 2026 – Complete Membership Guide, Documents, Fees & Registration Process🔹 Export Facilitation Scheme (EFS) 2026
Export Facilitation Scheme (EFS) 2026 – Complete Guide for Pakistani Exporters & SMEs🔹 Export Taxes in Pakistan
Complete Guide to Export Taxes in Pakistan – FBR Rules & Compliance🔹 Import & Export Consultancy
Import & Export Consultancy in Pakistan 2026 – PSW, WEBOC, Customs & Trade DocumentationFor Pakistani businesses, manufacturers, exporters and importers: GCCI membership can be an important part of building your business network and accessing trade-related opportunities. Understanding tax, customs and export-facilitation requirements can further help businesses prepare for local and international trade.
1
👥 Members
Community Members
- Sherry
- Waqas Dar
- Talha Masood
- ADMIN
- ZD Gold Fish
- Moqadis Tahira
- Rap Kreyòl
- Jason Smith
- Danial Hussain
- Riya
- Dany60
- Mudshar Ali
- Pakeeza Safdar
- morning star
- Ian Bell
- Vpneer Net
- Amaar Ali
- Paper Work Master
- Akfa kamli
- realhassan3
- Dental Restoration Pros
- Ezra Hidaya
- KVG Legend
- Fajas Fits
- Ανδρέας Ανδριόπουλος
- Muhammad Asad
- Emma White
- ayushiest
- Mirko Šimunjak
- Ainak_Wali_Churail
- barrybrennan
- h6k0n
- arlos YT
- XithyL
- Malik Wali
- PuTTy
- Aks e Khushbu
- Simon
- hazlejon
- Dangerous Gangster
- Irshadsultan
- stefanos 68
- d3m0n
- seoniloyislam1k
- Guru Samrat
- davidrae5124
- Anthony Riley
- KanekiTG
- Meeahsan
- kettlehobb
📊 Forum Statistics
Forum Statistics
Total Topics
Total Posts
🟢 Who Is Online
Who's Online (See full list)
- There are no registered users currently online